- Connect with our licensed Canadian insurance advisors
- Schedule a Call

Basics
Common Inquiries
BASICS
- Is Infinite Banking A Smart Financial Strategy?
- Understanding the Infinite Banking Concept
- Why Infinite Banking Appeals to Canadians Seeking Financial Freedom
- How Infinite Banking Strategy Helps Build Financial Independence
- Challenges and Misconceptions About Infinite Banking
- Who Should Consider Infinite Banking for Financial Freedom?
- How to Start Your Infinite Banking Journey
- Key Advantages of the Infinite Banking Strategy
- A Day-to-Day Struggle: Why More Canadians Are Exploring Infinite Banking
- Potential Drawbacks You Should Know
- The Future of Infinite Banking in Canada
- Is Infinite Banking a Smart Financial Strategy?
COMMON INQUIRIES
- Can I Have Both Short-Term and Long-Term Disability Insurance?
- Should Both Husband and Wife Get Term Life Insurance?
- Can I Change Beneficiaries on My Canadian Term Life Policy?
- What Does Term Life Insurance Cover and Not Cover?
- Does Term Insurance Cover Death?
- What are the advantages of Short-Term Life Insurance?
- Which Is Better, Whole Life Or Term Life Insurance?
- Do Term Life Insurance Rates Go Up?
- Is Term Insurance Better Than a Money Back Policy?
- What’s the Longest Term Life Insurance You Can Get?
- Which is better, Short-Term or Long-Term Insurance? Making the Right Choice
IN THIS ARTICLE
- What is the minimum income for Term Insurance?
- How Does Income Affect Your Term Life Insurance Policy?
- Can You Buy Term Life Insurance Online with a Low Income?
- How Can You Lower Your Term Life Insurance Cost?
- How Much Term Life Insurance Do You Need?
- Can Your Term Life Insurance Policy Be Adjusted Over Time?
- Why Term Life Insurance Is Ideal for Lower-Income Canadians
- Final Thoughts
- More on Term Life Insurance
Does A Life Insurance Plan Go Through Probate In Canada?
By Pushpinder Puri
CEO & Founder
- 13 min read
- Sep 24, 2026
SUMMARY
Life Insurance probate Canada rules can affect how quickly beneficiaries receive Life Insurance proceeds after the insured person dies. Probate fees, estate administration tax, beneficiary designations, tax liability, and probate law may all impact an insurance payout. Proper estate planning, Permanent Life Insurance, jointly owned assets, and updated Life Insurance beneficiary details in Canada can help families avoid probate, reduce estate costs, and protect wealth long-term.
Introduction
A family can work on developing their financial stability for thirty or forty years only to have the whole situation turned upside down when something unforeseen happens. It is precisely the harsh truth faced by most Canadian families annually. The family buys a Life Insurance contract, expecting to get the benefit money without delay once the insured passes away. However, upon the insured individual’s passing, it turns out that, for some reason, the Life Insurance settlement becomes delayed.
The fact is, we frequently communicate with people who believe that the proceeds from a Life Insurance Policy automatically fall outside probate in Canada. For example, there are cases where people do not even realize that their family’s estate became the owner of their Life Insurance Policy several years ago. Another thing is that some people have failed to update their beneficiary designation after a divorce, resulting in their ex-spouse becoming the new recipient.
This misconception is more relevant than ever before because estates have grown larger in Canada compared to what they used to be a generation back. As CLHIA reports, Life Insurance companies in Canada pay billions each year in Life Insurance death benefits. Meanwhile, the increasing value of property holdings, investments, the amount in RRSPs, and other business assets means that many estates will have to pay probate fees, estate administration tax, and taxes upon death.
Canadians wonder about the same things when they hear of cases of probate delays. What is probate? What does probate do? How long does probate take in Canada? Are Life Insurance payments subject to taxation under CRA rules? Does Life Insurance escape probate altogether?
All the above depend totally on how the insurance policy was set up prior to death.
Properly structured Life Insurance can enable a person’s estate to receive funds without taxes being charged and bypass the probate process entirely. However, failure to plan an estate or to maintain old documents may result in the estate having to go through probate, creditors demanding payments, and high estate taxes.
To avoid this, one must learn how the Life Insurance probate process works in Canada.
What Is Probate In Canada And What Does Probate Do?
Probate is the process by which a court certifies the validity of a deceased person’s will and empowers the estate trustee to deal with their estate. In Ontario, probate is related to Estate Administration Tax, which most Canadians refer to as probate fees.
People rarely consider probate until they undergo the process themselves. Most families believe that a will automatically bestows the authority on the executor. However, banks usually require certification before releasing funds or transferring ownership of assets.
The intention behind probate legislation is to safeguard everyone involved. Financial institutions, insurance providers, securities dealers, and land titles offices seek legal confirmation of the agent’s ability to represent the estate. Probate court effectively validates the will’s authenticity and identifies the agent empowered to act on the estate’s behalf.
After granting probate, the estate trustee may administer the estate’s property, settle debts, file tax returns, fulfill any legal duties, and distribute the inheritance to beneficiaries.
The challenge is that probate rarely moves quickly.
Families are quite shocked when they find out how long a will probate process can take in Canada. Probate can take anywhere from a few months to a lot more time, depending on the province and complexities involved, as well as court delays.
The reality is that this poses quite a challenge because you need to keep living your life despite probate delays. You have to pay your mortgage. You have to pay your utility bills. The cost of funerals needs to be settled right away. Spouses are left without their income while they wait for probate delays to resolve.
We always tell them that probate delay is not really the issue. The issue is how probate delays affect them.
When Probate Is Required In Canada
One of the major myths about probate and estate administration is that all estates undergo probate procedures automatically. This is not true.
The necessity for probate hinges mostly on how the estate assets were managed prior to death. Some assets are automatically transferred without undergoing probate, whereas other assets can only be transferred via probate. Jointly owned assets do not undergo probate since ownership transfers directly to the survivor. Registered assets where there is a beneficiary designation also avoid probate. Similarly, Life Insurance proceeds do not go through probate if there is a beneficiary designated.
Probate is more probable when the assets are individually owned or there are uncertainties regarding legal issues.
For instance, we have come across probate challenges that result from failing to update beneficiary forms due to divorce or marriage. There are also instances when there are no beneficiary designations at all, and there is no beneficiary left since he/she passed away several years ago.
Sometimes families unintentionally create probate problems simply because they assumed old paperwork was still valid.
Once the estate takes on this role, everything drastically changes. Beneficiaries no longer receive the insurance proceeds directly; rather, they are transferred to the estate of the insured individual. This could mean that the proceeds are then at risk from probate fees, estate administration tax, legal fees, creditors, and a delay in payment.
For example, one family in Ontario found themselves waiting many months before gaining access to the insurance proceeds when their father passed away. They had been relying on their father’s Life Insurance to help them through this difficult time. Years earlier, their father had chosen his estate as the beneficiary instead of naming a direct insurance beneficiary. What they had thought would provide some immediate income had turned into a long process of estate administration instead.
The point here is clear: estate planning is not something one does decades ago and forgets about it thereafter. Major changes in life could completely alter the structure of the insurance plan.
These changes include marriage, divorce, business ownership, retirement, births, and even deaths within the family.
Does A Life Insurance Policy Go Through Probate In Canada?
Life Insurance Policy Rules Most Canadians Misunderstand
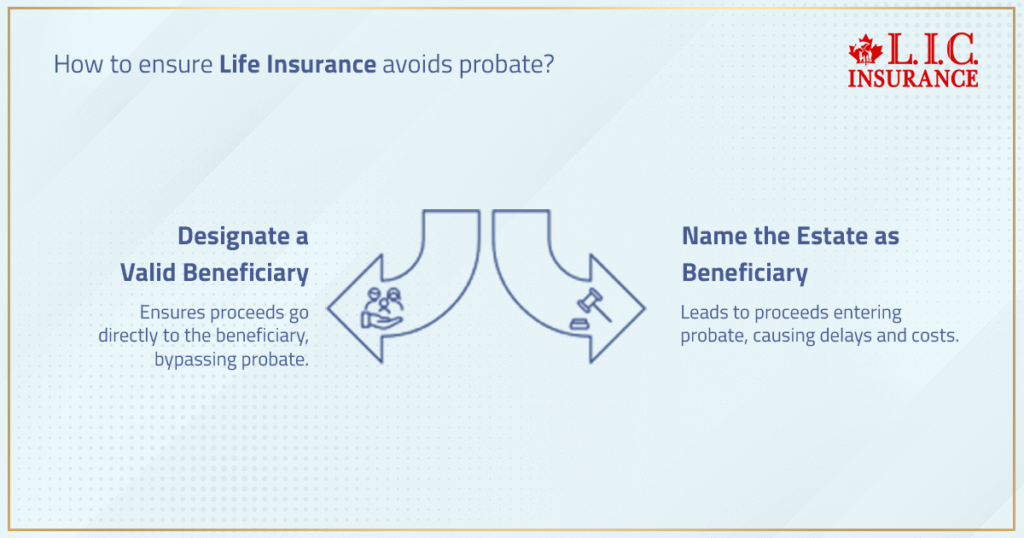
In most cases, Life Insurance will be outside the reach of probate as long as the insurance policy designates a valid beneficiary. This is what makes Life Insurance an effective tool for estate planning in Canada.
Upon death, the Life Insurance payment goes straight to the beneficiary named in the policy. Because the money does not become a part of the estate, there is no need to pay any probate or estate administration taxes.
This is the desired scenario.
But will Life Insurance be immune from probate in all circumstances? The answer is no. In certain cases, the proceeds from Life Insurance can end up in probate court.
The most common case involves naming the estate as the beneficiary of the policy. It is very popular among Canadians because they think it will make their estate planning easier.
The moment the estate becomes the designated beneficiary, the proceeds from the Life Insurance become an asset of the estate and can be involved in probate proceedings.
It is an emotionally and financially stressful situation at the worst possible time.
The widowed individual may find it difficult to pay bills before the process of probate is granted. Children might depend on Life Insurance to get educated and be supported. Entrepreneurs can be left with corporate liabilities despite the fact that estate settlement has not yet been completed.
Sometimes we tell our clients that the importance of Life Insurance is not just the face amount of the policy, but the fact that it is quick, sure, and secure in a tough period.
If the Life Insurance Policy is handled properly and avoids probate, then the family is able to get help in their time of need.
When Life Insurance Proceeds Become Part Of The Estate
Life Insurance Proceeds Can Accidentally Trigger Probate
Even one simple error in paperwork could drastically alter the treatment of the insurance settlement.
The family is shocked when they realize how simple it actually is for the insurance proceeds to inadvertently fall into the estate. This usually occurs because of either an invalid or outdated beneficiary designation.
It is common to find cases where a beneficiary died many years ago and yet he or she still remains listed as a beneficiary on the policy. There are other instances where individuals wrongly believed that their will would control the insurance settlement.
Once the insurance proceeds are part of the estate, everything becomes different.
The proceeds may become vulnerable to creditors and the probate process. Probate fees might be applicable. Estate administration tax might affect the net value of the estate.
The emotional significance of this experience tends to be understated. Those anticipating an easy process of receiving insurance money are confronted with a process that involves legal documents and waiting periods.
This process becomes all the more challenging when the survivors depend heavily on this money to replace their income. The funeral expenses are paid out right away. The mortgage payments remain as scheduled. Tax responsibilities related to any RRIFs, investments, and businesses may start having an effect on the estate, too.
An estate plan could turn a potential problem into a solution.
How Beneficiary Designations Help Avoid Probate
The problem for many people in Canada is that they concentrate too much on making their will but fail to consider the beneficiaries named on their insurance policies and registered investments. This is very dangerous and can cause problems further down the road.
In general, the insurance company will consider the most recent beneficiary designation that has been made on the insurance policy. The will could say one thing, but the beneficiary form may have taken precedence.
This will come as a shock to many families.
We strongly recommend that our clients update their beneficiaries whenever there has been a significant change in their lives because things keep changing and evolving.
One of the most frequent issues that arises is in relation to divorce. An individual gets remarried, forms a new family, and feels that their estate plan automatically takes care of any changes. However, after some time passes, the ex-spouse might remain the named beneficiary of the Life Insurance Plan because the beneficiary form was never changed.
For example, we once checked a Life Insurance Policy for a business owner from British Columbia who had been divorced nearly a decade ago and had not taken the time to change the beneficiary form. After the individual passed away suddenly, the beneficiary claimed on the Life Insurance Policy, which was claimed by the ex-spouse since the form remained the same with the insurance company. The family assumed that the will overrides everything else, but the probate laws were clear that the beneficiary designation should be considered independently from the estate.
Another significant issue has to do with designating a minor child as a beneficiary, which requires additional steps because a minor cannot manage money in accordance with the laws in many provinces.
However, all of these concerns are easily preventable as long as the individual reviews the estate plan regularly.
Are Life Insurance Proceeds Taxable In Canada?
One of the major misconceptions about Life Insurance probate in Canada is the issue of taxation.
Many Canadian residents mistakenly think that the tax on insurance payable to the Canada Revenue Agency applies to all insurance payments. Thankfully, Life Insurance proceeds for death benefits going to a designated beneficiary are tax-free in Canada.
This implies that beneficiaries are likely to be exempt from taxes on the insurance payment from the Life Insurance Plan itself.
However, there is confusion when it comes to tax liabilities arising from other sources within the estate.
The balances in RRSPs, RRIFs, real estate, businesses, and non-registered investments may be taxed even after someone passes away. The problem is that many families tend to associate these taxes with the Life Insurance payments when they really have nothing to do with each other.
There is also an additional element of taxation for Permanent Life Insurance Policies and Cash Value Life Insurance in Canada, depending upon their application within the individual’s lifetime. Policy loans, surrender values, withdrawals, and changes of ownership can be taxed in certain conditions.
This is the reason that estate planning and tax planning must go hand in hand in many cases. We frequently coordinate with the assistance of accountants and tax experts to ensure that the planning for Life Insurance becomes easier without tax obligations.
How Permanent Life Insurance In Canada Helps With Estate Planning
The benefits of Permanent Life Insurance are far more extensive than just providing income replacement.
Quite frequently, Canadian consumers rely on permanent insurance as part of their ongoing estate planning process.
Unlike Term Life Insurance, which only provides insurance coverage during an allotted period of time, Permanent Life Insurance offers both a lifetime of coverage and a way to grow funds over time.
For that reason, permanent insurance is an invaluable tool for any family facing estate tax issues in the future.
One situation we often come across relates to family cottages.
Typically, such cottages were purchased years ago for less money, and now their value has increased tremendously.
After the owner’s death, even though no sale took place, the property will generate capital gains taxation.
The lack of liquidity forces family members to sell the cottage merely because of paying off capital gains tax.
With Permanent Insurance, the insured could instantly receive funds that would serve to cover these costs without paying taxes on the withdrawal.
In business, people tend to employ the same tactics for shielding assets from any loss, safeguarding the interests of the stockholders, and facilitating continuity in their business.
For numerous families, permanent insurance ceases to be an insurance plan and turns into protection for financial security.
Life Insurance Payout Timelines Vs Probate Timelines
| Situation | Typical Timeline |
|---|---|
| Named Beneficiary | Faster |
| Estate Named Beneficiary | Slower |
| Probate Court Delays | Much Longer |
| Contested Estate | Potentially Extensive |
When Life Insurance proceeds go through probate correctly, beneficiaries usually receive the money fairly quickly once all the necessary papers have been filed.
However, when probate intervenes, there can be significant delays.
As we like to say, time is just as important as the amount of money from an insurance policy. Very few families have the luxury of waiting months before continuing.
The bills keep coming even after someone passes away. Mortgage payments are due on time. The children still need to eat. There may also be business dealings that continue.
That is where the importance of beneficiary designations comes into play.
Probate Fees In Ontario And Across Canada
| Province | Probate Fee Structure |
|---|---|
| Ontario | Estate Administration Tax Based On Estate Value |
| British Columbia | Percentage-Based Probate Fees |
| Alberta | Lower Flat Probate Structure |
| Quebec | Different Civil Law Estate Process |
In the past, probate mostly involved only very rich families with significant estate holdings. However, nowadays, with rising real estate prices and investments, regular middle-class Canadians are becoming more prone to paying probate costs as well as possible inheritance taxes.
This is one of the factors that makes Life Insurance Plans, designation of beneficiaries, joint tenancy arrangements, and other tax-planning measures highly important in today’s estate planning debates.
How Jointly Owned Assets And Registered Accounts Affect Probate
There may be some assets that do not require probate if structured properly.
In most cases, joint property will automatically transfer to the surviving spouse through the probate process.
Tax-Free Savings Account, registered retirement savings plan, and registered retirement income fund are also likely to avoid probate if they are set up properly with appropriate beneficiaries named.
Such steps will help individuals save on probate expenses.
But probate avoidance is never the ultimate objective.
Poor ownership structure can lead to various problems, including tax issues, legal complications, and even family conflicts.
It is important for our clients to understand that a well-rounded estate planning approach involves balance.
Our goal is not to avoid probate at any cost.
Potential Estate Taxes Canadians Often Overlook
Canada does not have an inheritance tax, but nevertheless, many estates end up facing considerable tax liabilities after death.
The various tax liabilities include registered funds, investments, businesses, and capital gains. Many families are unaware of just how quickly the value of their estates can be eaten away through taxation before the beneficiaries actually receive any money.
That’s one of the reasons why Permanent Life Insurance continues to be an important asset in the process of estate planning.
The story of a retired couple living in Alberta includes a family cottage, some non-registered investments, and some registered retirement income funds that have appreciated significantly. When one member of the family died, the other realized that there were substantial tax liabilities arising out of capital gains and registered accounts taxes. Permanent Life Insurance came in handy when it came to paying the estate taxes, and the sale of the family cottage was avoided.
Proceeds from an insurance policy will give you instant access to money, which could be used to pay taxes, retain your investments, and avoid selling off valuable assets of your family just to meet tax needs.
Our firm often advises our clients on how to utilize a Permanent Life Insurance Policy to protect their heirs from the burden of any further financial pressure in relation to estate taxes and probate.
Strategies Canadians Use To Avoid Probate Legally
Most Canadians prefer not to have their loved ones involved with probate delays and legal issues following their death.
There are several methods that can help lower probate risk, including well-planned beneficiary designations, joint ownership, Life Insurance Planning, trusts, and coordinated tax planning.
A Life Insurance Policy continues to be one of the best ways to plan your estate for probate risks, especially when beneficiaries have been properly named, allowing them to collect the funds outside probate.
However, planning to avoid probate must always be done with professional advice. Bad planning could result in unforeseen consequences, including creating unnecessary tax problems or other disputes among family members.
We routinely collaborate with attorneys, accountants, and financial planners to assist in structuring an estate plan.
How Canadian LIC Helps Families Protect Their Estate And Life Insurance Benefits
Estate planning isn’t just about filling out documents. It’s about safeguarding actual families through trying times.
Our attorneys assist clients in assessing their beneficiaries, their need for probate, comparing different types of Permanent Life Insurance, and developing the best Life Insurance Plans that safeguard their surviving loved ones financially.
We also compare solutions from insurers such as:
- Manulife
- Sun Life
- Canada Life
Every family’s circumstances are different.
Some families are interested in reducing probate costs. Some families may be more interested in protecting their wealth, business succession planning, or asset preservation.
The best course of action is determined by each individual family’s needs, tax obligations, and financial considerations.
Final Thoughts
The majority of Life Insurance benefits in Canada are spared from the requirement of undergoing probate as long as there is a valid beneficiary designation in the insurance policy. However, the lack of attention paid to the contents of one’s estate plan could result in probate fees, estate administration tax, legal costs, and even delays in insurance money being collected by family members at a crucial point in time.
A carefully constructed insurance policy will help beneficiaries gain access to tax-free funds quickly without any stress on them or financial strain on the family.
However, when it comes to Life Insurance that does not have a valid beneficiary designation, such insurance money is subject to probate just like any other asset in the estate.
In fact, awareness of this regulation beforehand will allow survivors to benefit greatly from understanding these rules during a time of need.
In today’s world, examining one’s insurance policy and estate planning strategy could very well be the most important financial decision made by many Canadians.
Author: Harpreet Puri, Licensed Insurance Adviser | MDRT Qualifier
Experience: 14 Years In Life Insurance & Financial Planning
LinkedIn Profile:https://www.linkedin.com/in/harpreetpuricanadianlic/
Disclaimer:
This content is intended for general educational purposes only and should not be considered legal, tax, or financial advice. Probate law, estate administration tax, and Life Insurance beneficiary Canada rules may vary by province and individual circumstances. Readers should consult qualified legal, tax, or financial advisors before making estate planning or Life Insurance decisions.
FAQs
In scenarios involving simultaneous death, there may be challenges faced during the probate process. Lack of a contingent beneficiary within the Life Insurance contract may make matters difficult since the Life Insurance monies may have to be distributed to the estate of the deceased first before legal issues are sorted out.
Of course, there is no issue here regarding the receipt of benefits from a Canadian insurance company by a foreigner, provided that there was some form of designated beneficiary. But one should consider other factors such as taxation, banking regulations, and other issues regarding identification when dealing with the insurance payment.
Funeral costs are immediately a burden since probate court clearance takes several months in some provinces. Most people opt to use their savings until they have access to the money from the deceased’s estate or the benefits from Life Insurance. Having an appropriately planned Life Insurance beneficiary in Canada may solve this problem.
Problems could occur in terms of probate law regarding digital wills and estate plans that lack proper witnessing based on the rules of each province. Should there be any doubts regarding the will’s legitimacy by the probate court, there is the potential for significant delays during estate administration.
When an insurance policy expires due to failure to pay premiums, the beneficiaries could be left without the Life Insurance benefit. In such situations, surviving partners whose lives depend on Permanent Life Insurance would face significant difficulties. It is important for policyholders to conduct regular reviews of their policies.
Yes, the delay in the probate process will pose significant operational problems when corporate interests are included in the deceased person’s estate. Bank accounts, shareholding agreements, and other outstanding obligations may be hard to manage without the authorization of the estate trustee. Businesspersons who incorporate their businesses tend to acquire permanent insurance.
The compensation payable to the executor or trust estate administrator may be regarded as taxable income based on how it is paid out and how each province handles the probate laws. Estate administration usually leads to more taxable items beyond the costs associated with the probate process itself.
Yes, it is true that proceeds from Life Insurance Policies are utilized to finance dependent children with disabilities via estate planning mechanisms and trusts. The use of a well-crafted insurance policy may help families extend their benefits tax-free without interfering with other programs run by the government.
Certainly, an increase in real estate values can affect estate administration taxes and the potential estate taxes since the value of the estate will be considerably higher. Often, families find themselves surprised by how large the probate costs will be due to the increase in real estate values.
Many cases involving estate disagreements arise because the beneficiary paperwork was never changed after any divorces, subsequent marriages, or business ownership shifts. The family assumes that their deceased individual meant to have other beneficiaries named than the ones the insurance company has on file.
The majority of Canadian Life Insurance companies will check on the validity of the beneficiaries designated prior to paying out money on a death Life Insurance Policy. The existence of a valid beneficiary will often ensure that the insurance payout is made outside of the process of probate and distributed to the beneficiaries without delay.
One of the easiest methods of ensuring that your Life Insurance proceeds will not be subject to probate expenses in Canada is by keeping up-to-date the beneficiary designation forms with a proper designated beneficiary. It is equally important for family members to check up on their Life Insurance Coverage periodically following a significant event such as marriage, divorce, or retirement.
Term Life Insurance and Permanent Life Insurance in Canada, like any other Life Insurance, can avoid going through probate depending on how the beneficiaries are set up. The determining aspect in this case is normally not the kind of Life Insurance but whether the insurance amount is paid out directly to the beneficiary.
It is possible that a properly structured non-probate Life Insurance Plan will allow families to be able to obtain funds from their insurance much more quickly than they otherwise would have without paying extra fees and expenses, including legal expenses and stress. Life Insurance Plans are frequently utilized in Canada to ensure protection against financial hardship.
The designated beneficiary becomes very important when it comes to deciding whether the proceeds from the policy will go through probate or not. If all is well with the beneficiary designation, then the beneficiaries are likely to get money faster without being subject to creditors and probate issues.
Sources and Further Reading
- Canadian Life And Health Insurance Association (CLHIA) – Consumer Guides — Official Canadian insurance industry educational resources covering Life Insurance, beneficiary designations, estate planning considerations, and consumer protection.
- Canadian Life And Health Insurance Association (CLHIA) – About The CLHIA — Information about Canada’s primary life and health insurance industry association representing most Canadian insurance companies.
- Canada Revenue Agency – Doing Taxes For Someone Who Died — Official CRA guidance explaining estate tax obligations, final returns, and tax responsibilities after death.
- Canada Revenue Agency – Clearance Certificate For Estates — CRA explanation of estate clearance certificates, estate liabilities, and tax obligations connected to probate and estate administration.
- RBC Insurance – What Is A Life Insurance Beneficiary? — Canadian explanation of beneficiary designations, contingent beneficiaries, probate delays, and tax-free Life Insurance proceeds.
- Ontario Government – Estate Administration Tax — Official Ontario government information regarding probate fees, estate administration tax, and probate calculations in Ontario.
- Ontario Courts – Estate Procedures And Probate Applications — Ontario probate application process and estate trustee procedures.
- People’s Law School – Naming An Estate As A Beneficiary — Legal discussion on how naming the estate as beneficiary may affect probate exposure and Life Insurance proceeds.
- Sun Life – Cash Value In Life Insurance — Explanation of Permanent Life Insurance, cash value accumulation, and tax considerations in Canada.
- TD Wealth – Estate And Inheritance Tax In Canada — Educational resource discussing estate taxes, probate and estate administration, and tax liabilities after death.
Key Takeaways
- Most Life Insurance proceeds in Canada can bypass probate when a valid beneficiary designation exists on the insurance policy.
- Probate and estate complications often happen because beneficiary forms were outdated, missing, or incorrectly structured.
- Naming the estate as beneficiary may expose Life Insurance proceeds to probate fees, estate administration tax, legal costs, and creditor claims.
- A properly structured Life Insurance Policy can help families receive tax-free financial support faster after the insured person dies.
- Probate law and estate planning rules vary across Canada, especially regarding probate fees and estate administration procedures.
- Permanent Life Insurance and Cash Value Life Insurance in Canada are often used for wealth protection, tax planning, and covering potential estate taxes.
- Registered retirement savings plan balances, business interests, and investment properties may create tax liability even when Life Insurance proceeds remain tax-free.
- Reviewing beneficiary designations after major life events like marriage, divorce, retirement, or business ownership changes is extremely important.
- Jointly owned assets and registered accounts may help families avoid probate when structured properly within a comprehensive estate plan.
- Working with experienced financial advisors, tax professionals, and estate planning specialists can help families protect assets and reduce future probate-related financial stress.
Your Feedback Is Very Important To Us
IN THIS ARTICLE
- Does A Life Insurance Plan Go Through Probate In Canada?
- What Is Probate In Canada And What Does Probate Do?
- When Probate Is Required In Canada
- Does A Life Insurance Policy Go Through Probate In Canada?
- When Life Insurance Proceeds Become Part Of The Estate
- How Beneficiary Designations Help Avoid Probate
- Are Life Insurance Proceeds Taxable In Canada?
- How Permanent Life Insurance In Canada Helps With Estate Planning
- Life Insurance Payout Timelines Vs Probate Timelines
- Probate Fees In Ontario And Across Canada
- How Jointly Owned Assets And Registered Accounts Affect Probate
- Potential Estate Taxes Canadians Often Overlook
- Strategies Canadians Use To Avoid Probate Legally
- How Canadian LIC Helps Families Protect Their Estate And Life Insurance Benefits
- Final Thoughts
Sign-in to CanadianLIC
Verify OTP