Canadianlic

How Age Affects $1M Life Insurance Cost (2026 Guide)
How Age Affects $1M Life Insurance Cost (2026 Guide)
How Age Affects $1M Life Insurance Cost
Canadian LIC

By Harpreet Puri

CEO & Founder

SUMMARY

$1M Life Insurance cost by age shows how monthly premiums rise over time and why the best age to buy Life Insurance matters. Term Life Insurance $1 million cost remains the most affordable for high-value Life Insurance Plans, while Million Dollar Whole Life Insurance in Canada builds cash value. Health class, medical exam results, and coverage amount shape pricing and long-term financial protection.

Introduction

Why $1M Life Insurance Coverage Is A Financial Necessity In Canada

There is a subtle change happening in Canadian households as well. While high coverage used to be quite unusual some years ago, nowadays it is the norm. One million is not too large an amount to be required in the field of Life Insurance because of the financial situation in this country. In other words, according to the information provided by the Canadian Life and Health Insurance Association, there are millions of people in this country who use the help of Life Insurance Policies in order to protect their income and finances.

Canadian LIC have over 15 years of experience in assisting individuals and families in comparing several Life Insurance companies and choosing the most affordable one.

It becomes quite clear from everyday interaction with customers that a large amount of money is needed for Life Insurance. Just think of the average mortgage in Canadian cities: it can amount to hundreds of thousands of dollars. Plus living costs and kids’ education, the final sum is equal to or is even more than one million. That is why Million Dollar Life Insurance Coverage has become rather popular nowadays.

$1M Life Insurance Cost By Age – What You Pay At Every Stage

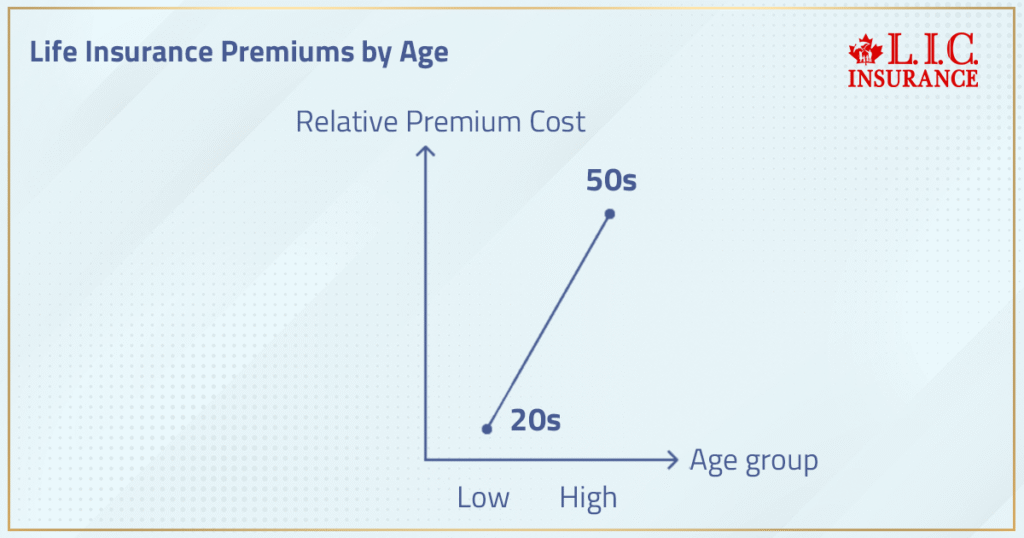
Age is one of the most important considerations that determines Life Insurance prices. Age is a straightforward metric, yet its implications are immense. With younger applicants, life expectancy is higher, and the risk for insurers is low. However, as age advances, the likelihood of claiming rises significantly, and monthly premiums become more expensive.

According to real pricing trends from various insurers like Sun Life Financial, Manulife, and Canada Life, the disparity in the price of $1 million Life Insurance varies dramatically based on age. For instance, an average person in their twenties who applies for Life Insurance will have a much cheaper premium compared to someone in their fifties with similar amounts.

Rate class and health class should also be noted in this context. Insurers consider health issues, past illnesses, lifestyle choices, and familial history to estimate risk levels. Two individuals in the same age bracket could end up paying entirely different premiums due to their preferred, standard, and sub-standard risks.

Many people are often shocked to discover that the rise in price with age is exponential rather than linear. While waiting for five to ten years may appear trivial, it may mean twice or thrice the current monthly premiums.
Life Insurance Premiums By Age

Sample Monthly Premiums For A Million Dollar Policy In Canada

Term Life Insurance $1 Million Cost (Estimated – Non-Smoker, Average Health)

These are sample monthly premiums and represent typical premiums for healthy individuals in an average health class by multiple companies. Although the exact premiums will differ based on underwriting results, the key point illustrated here is that there is a compound impact of age on cost.

When we provide Million Dollar Life Insurance quotes to our clients, the biggest money decision they make is whether to purchase their policies early or late. This is where you have the same amount of coverage, same terms, and the same coverage, but your premium differs based on when you buy.

Whole Life Insurance Cost for $1 Million Coverage

Whole Life Insurance follows a distinct approach to its operation. As opposed to Term Life Insurance, where the policyholder is covered for a specified duration of time, Whole Life Insurance Coverage is perpetual and comes with a savings element.

Example (Non-Smoker – From Sun Life Financial Data):

These Whole Life Insurance estimates are illustrative and based on aggregated pricing trends across major Canadian Life Insurance companies, including Sun Life Financial. Actual premiums vary based on health class, policy structure, and underwriting outcomes.

(Source: https://www.sunlife.ca/en/insurance/life/permanent-life-insurance/whole/whole-life-insurance-rates-in-canada/) 

These figures represent the cost of Permanent Coverage. These increased premiums do not result from age alone; rather, they represent lifetime coverage, the buildup of cash value, and a certain payment in the future.

Whole Life Insurance in Canada tends to be part of more sophisticated planning, such as estate planning and pension income planning. The possibility of building up cash while at the same time having lifetime insurance coverage renders Whole Life Insurance a viable option for people with financial goals in the long run. But for those interested only in income replacement and low-cost insurance, Term Life Insurance is much cheaper.

Term Life Insurance Vs Whole Life Insurance Cost

The choice of Term versus Whole Life Insurance usually hinges on the intent of the policyholder. The former will provide adequate cover for protecting earnings in the prime earning years; the latter will go beyond this basic function and serve other financial objectives. But when it comes to expenses, there is little doubt.

Term Life Insurance delivers the same payout for a much smaller price tag, thereby making it the best choice for those who wish to have high-value Life Insurance Policies at affordable costs.

How Health Class Impacts Million Dollar Life Insurance Premiums

Even though age remains the main criterion, the health class will play an equally important role in setting up the insurance premium. An extensive list of parameters needs to be considered prior to allocating the insured person to a certain rate class.

People with good health conditions that allow them to get preferred rates will have much lower monthly premiums compared to individuals who face certain problems with their health condition, like hypertension, diabetes, or a habit of smoking.

Smokers generally cost significantly more compared to non-smokers. This discrepancy is due to the extra level of risk that comes about owing to lifestyle considerations. Differences in health conditions among non-smokers may also affect costs.

It is not uncommon to have clients surprised at how much health matters in terms of cost when it comes to insurance. Two people with identical coverage periods might end up paying quite different premiums owing to the class of their health condition.

Million Dollar Life Insurance Policy Without A Medical Exam

The world of insurance has undergone a great transformation with the advent of accelerated underwriting. Nowadays, most companies dealing with Life Insurance offer products that do not entail a medical examination, meaning one can obtain insurance within minutes.

This convenience comes at a price, however. Products that do not necessitate a medical examination cost more since insurers make judgments on the basis of incomplete information. Instead of conducting a comprehensive medical exam, insurers examine the health history, medication history, and other digitally available information.

A medical examination may help to cut costs for applicants in good health by allowing insurers to conduct comprehensive underwriting.

The Best Age To Buy Life Insurance (Critical Insight)

There is no doubt that the one major thing which stands out among all is that the best time to invest in a Life Insurance Plan is the earliest possible time. Mathematics always proves this statement true.

When someone decides to buy a Life Insurance Policy worth a million dollars at the age of twenty, then he or she manages to get low payments on a monthly basis for several years to come. On the other hand, the very same person buys a similar policy later at the age of forty or fifty, then he or she will pay much higher amounts for that.

Real Scenario: Waiting Costs More Than You Think

Scenario: Same Coverage ($1M, 20-Year Term)

This situation brings out an absolute truth about Life Insurance. The level of coverage will be the same. The death benefit will not change. However, the overall amount payable will vary greatly depending on when the purchase was made.

A delay in making a purchase for a period of ten years would increase the overall amount to twice its value. Waiting for twenty years would raise it many times more than this.

How Much Coverage Do You Really Need?

The amount of Life Insurance Coverage one should have will depend on their personal financial liabilities. There is generally a rule of thumb, whereby one’s coverage will be ten to fifteen times their annual income, but more often than not, reality is different from this rule.

A person’s mortgage, daily living, cost of schooling, and provision of finance to take care of dependants into the future are all considerations. For most people, a minimum of $1 million in coverage will be ideal.

Our experience shows that people who purchase insufficient insurance will end up changing their plans in the future. Changing coverage when a person is older will only result in expensive premiums.

Choosing The Right Life Insurance Companies In Canada

The Canadian insurance industry comprises many established companies that are recognized for their strong claim-paying ability and sound finances. In addition to this, Canadian LIC collaborates with several federally insured companies that work according to the guidelines set by the Canadian Insurance Act and the province, which include the Financial Services Regulatory Authority of Ontario. It is important that all recommendations comply with the required laws, rules, regulations and standards related to compliance and consumer protection, along with insurers’ claim paying abilities. 

Companies such as Sun Life Financial, Manulife and Canada Life are always rated among the top insurance companies. Each insurer has its own set of underwriting criteria and pricing schemes. That is why it is crucial to compare at least two carriers.

Using the brokerage service enables you to compare several companies at once and get the best pricing and adequate coverage.

Why Regulatory Oversight Matters In Life Insurance

The Canadian Life Insurance system is regulated according to strict regulations. Provincial financial services agencies, for instance, the Financial Services Commission of Ontario, license and regulate Life Insurance companies, and industry organizations, such as the Canadian Life and Health Insurance Association, provide guidance and reporting guidelines. Through this process, insured individuals can benefit from financially secure insurance institutions.

Strategies To Lock In Affordable Million Dollar Life Insurance

Finding affordable insurance has less to do with taking shortcuts and more to do with timing, physical well-being, and smart decision-making. Buying Term Life Insurance early, staying healthy, and choosing the right term all help in making insurance cheaper.

Shopping around for better prices among competing insurance firms helps ensure that consumers don’t pay more for something worth just as much. Small differences in premium payments may amount to substantial savings in the long run.

Nevertheless, nothing beats good timing. Waiting simply means paying more in the end.

Million Dollar Life Insurance Payout – What Your Family Receives

A Million Dollar Life Insurance payout offers financial help at a crucial time. It does not attract tax in Canada, and so the money is all yours to do with as you wish.

It helps pay off debt, provides income for your family, and stabilizes finances for the future. The Million Dollar Life Insurance payout is your foundation.

Final Thoughts On Securing A Million Dollar Policy At The Right Age

The impact of age on Life Insurance costs extends to every facet of the equation, from the beginning of the process to its sustained feasibility. The contrast between the two approaches goes beyond mere dollars; it encompasses freedom and assurance.

One million dollars in coverage represents much more than a mere figure; it symbolizes a dedication to safeguarding financial obligations, ensuring that one’s family and legacy will thrive.

From the standpoint of the Canadian Life Insurance Company, the trend holds true time and time again. Those who take initiative benefit from favourable prices, a wider range of options, and overall financial efficacy.

Written By: Harpreet Puri

Licensed Insurance Adviser | MDRT Qualifier

With over 14 years of experience in Life Insurance, wealth planning, and tax-efficient strategies for Canadians.

Disclaimer:

This content is for informational purposes only and does not constitute financial or insurance advice. Premiums, coverage, and eligibility vary by insurer, health class, and underwriting. Examples are estimates and may differ from actual quotes. Consult a licensed advisor before making decisions.

Get The Best Insurance Quote From Canadian L.I.C
Call +1 416-543-9000 to speak to our advisors.
Get Quote Now

FAQs

Most Term Life Insurance Plans have the provision for converting the plan into a permanent Life Insurance Plan without the need for a new medical examination. An individual who has a $1 million Term Life Insurance Plan and is paying around $55 per month can convert the plan into a permanent one when he is about 45 years old; however, he might have to pay $400-$700 per month now.

A million dollars can lose its worth through the effects of inflation. With the average inflation rate at 3%, for instance, $1,000,000 is worth about $550,000 after 20 years. Fortunately, there are certain types of Life Insurance that provide the option to gradually increase the policy limit.

In Term Life Insurance, the monthly payments remain constant throughout the selected period. Thus, if you pay $45 per month for 20 years starting at 30 years old, your monthly payments will be constant until 50 years old. In the case of Permanent Life Insurance, the premiums can fluctuate, depending on the policy design.

Permanent Life Insurance is indeed often employed for estate planning purposes. An example of this would be a $1 Million Dollar Policy that helps offset the capital gains tax due on the sale of investment property, where the capital gains tax might amount to $300,000 or more.

The approval process depends on the underwriting process. Traditional insurance products that need a medical examination can be processed within 2 to 6 weeks. Faster underwriting processes can provide approval of an insurance product worth $1 million within just a few hours or days.

When your health condition gets better, you might become eligible for a different premium classification upon applying again. As an instance, a person who pays around $120 per month for term insurance as a smoker aged 40 can decrease his monthly premiums to roughly $70 by living one year as a non-smoker.

Premiums differ according to age and risk classification; however, major players in the Life Insurance market, including Sun Life Financial, Manulife, and Canada Life, always provide competitive premiums. A young adult who is classified as healthy can pay premiums ranging from ~$40-$55 per month, while someone in their 50s may be required to pay premiums of ~$180-$320 monthly.

Yes, today most insurance providers offer online tools that will calculate a one-million-dollar insurance quote online. The tools take into account the person’s age, his or her health condition, and the amount of coverage sought. For example, using age thirty-five and excellent health can produce an approximate Term Life Insurance cost of $50 per month, while changing the age from thirty-five to forty-five can raise the cost to $95-$120 per month.

The difference is significant because of life expectancy as well as risk. While the monthly premium paid by a healthy individual at 30 years old for a One Million Dollar Policy under Term Life Insurance is likely to be ~$40-$60, by the time that person turns 60 years old, he/she could end up paying ~$350-$700+.
Sources and Further Reading

(Life Insurance rates in Canada, including age-based pricing examples for Term Life Insurance)

(Whole Life Insurance pricing, cash value growth, and long-term cost factors)

(Factors affecting Life Insurance cost, including age, health class, and coverage amount)

(Term Life Insurance structure, coverage options, and how premiums vary by age)

(Insights on the best age to buy Life Insurance and how timing affects premiums)

(Term Life Insurance features, coverage ranges, and online quote availability)

(Regulation, licensing, and consumer protection standards for Life Insurance in Canada)

Key Takeaways

  • Age Drives $1M Life Insurance Cost The Most
    The difference in $1M Life Insurance cost by age is significant—buying in your 20s or 30s locks in much lower monthly premiums compared to waiting until your 40s or 50s.
  • Term Life Insurance $1 Million Cost Remains The Most Affordable Option
    Term Life Insurance provides the same death benefit at a fraction of the cost, making it the preferred choice for High Value Life Insurance Plans focused on income replacement.
  • Whole Life Insurance Offers Lifelong Coverage But Higher Premiums
    Million Dollar Whole Life Insurance in Canada includes a cash value component and permanent coverage, but comes with a substantially higher monthly cost.
  • Health Class And Medical Exam Strongly Impact Pricing
    Your health status, medical history, and lifestyle factors determine your rate class, directly affecting Life Insurance cost and final premiums.
  • Delaying Your Decision Increases Long-Term Costs
    Waiting even a few years can double or triple Million Dollar Life Insurance premiums for the same coverage amount and term length.
  • Coverage Amount Should Match Real Financial Responsibilities
    A Million Dollar Policy helps cover mortgage balance, living expenses, income replacement, and final expenses, ensuring long-term financial protection.
  • Comparing Multiple Insurance Companies Helps Reduce Costs
    Shopping across providers like Sun Life, Manulife, and Canada Life can reveal better monthly rates for identical coverage.
  • No Medical Exam Policies Offer Speed, But At A Higher Cost
    Accelerated underwriting allows faster approvals, but policies without a medical exam typically come with higher premiums.
  • Timing And Health Are The Biggest Cost Advantages
    Securing Life Insurance early while in good health ensures affordable coverage and protects against future health-related pricing increases.

Your Feedback Is Very Important To Us

    1. Full Name:

    2. Email Address:

    3. Before reading, how familiar were you with the $1M Life Insurance cost by age?

    4. What is your current age range?

    5. Do you currently have a Life Insurance Policy?

    6. If yes, what type of Life Insurance Coverage do you have?

    7. What coverage amount do you currently hold (if any)?

    8. What is your biggest concern when considering a $1M Life Insurance Policy?

    9. Have you delayed buying Life Insurance due to cost concerns?

    10. What has been your biggest challenge in getting a Million Dollar Insurance quote?

    11. What matters most when choosing Life Insurance companies?

    12. What would make you more confident in buying a Million Dollar Life Insurance Policy?

    13. Are you planning to buy or review Life Insurance in the next 6 months?

    14. Would you like a personalized $1M Life Insurance quote based on your age and health?

    15. Any additional questions or concerns about Life Insurance cost, coverage amount, or financial protection?

    High-Value Life Insurance In Canada: Why Coverage Over $1 Million Matters

    High-Value Life Insurance In Canada: Why Coverage Over $1 Million Matters

    High-Value Life Insurance In Canada Why Coverage Over $1 Million Matters
    Canadian LIC

    By Harpreet Puri

    CEO & Founder

    SUMMARY

    A Million Dollar Life Insurance Policy isn’t a luxury—it’s smart protection. With rising living costs, debts, and family responsibilities, Canadians need higher coverage for true financial security. This guide from Canadian LIC explains why coverage over $1 million matters, how cash value and Permanent Life Insurance Policies build long-term wealth, and how to choose the best Life Insurance Plans in Canada for your family’s future.

    Introduction

    A Million Dollar Life Insurance Policy isn’t about luxury or showing off. It’s not about flaunting wealth — it’s about showing up for the people who count on you. Many Canadians believe a smaller policy will suffice, but when they add up mortgage loans, tuition fees, caregiving for families or business debts, the harsh truth hits: half a million doesn’t go as far as it once did. Increasing living costs, longer lifespans, and the financial responsibilities families have today have upended what is truly enough protection.

    We witness this reality daily. Families come to us believing they have “enough coverage,” only to learn that after taxes, debts and inflation, their survivors would be hard pressed to make ends meet. That’s why we’re not talking about Million Dollar Life Insurance Policies as some sort of luxury; it’s because they are an affordable form of financial protection specifically tailored for today’s Canadian families.

    How Much Life Insurance Is Truly Enough?

    A lot of people don’t even stop to figure out how much Life Insurance they need in the first place. They choose a number that sounds all right — $250,000 or $500,000 — and move on. But when we do the math together, that comfort zone disappears real quick.

    Think about it. If you make $100,000 a year and your family depends on that income for ten years, then, already, your replacement need alone creeps up to the million-dollar mark. And that’s not even counting mortgages, education expenses or debts carried from the past. That’s why a $1 million Life Insurance Policy is actually reasonably sized coverage, not excessive.

    Such coverage offers families more than money; it gives them continuity. It guarantees mortgage payments continue, children’s education is not derailed, and surviving spouses remain on a path toward long-term financial security. That’s what Life Insurance Coverage is designed to do — maintain stability when life itself gets dicey.

    Why Canadians Are Re-Evaluating Their Insurance Coverage

    For the past few years, the conversation around money has changed. The cost of living has skyrocketed — housing prices, the price of education, groceries, and health care — all rising more rapidly than incomes. A tiny policy that might have looked “safe” now covers a few years of expenses at best.

    We want to remind clients that Life Insurance Coverage should change as their financial situation changes. If your mortgage balance, the value of your business, or the size of your family has increased, so should your insurance. When you’re replacing decades of earned income and trying to keep an accumulation of assets that you spent your life building, a million dollar policy in coverage sounds a lot less big.

    Why A Million Dollar Policy Is About Financial Security, Not Vanity

    Let’s clear one thing up. The money in a Million Dollar Life Insurance Policy isn’t all about you—instead, it’s money to take care of your loved ones when you’re gone. It’s making sure the roof stays over their heads, that they can pay the bills and find a way to make those someday dreams happen.

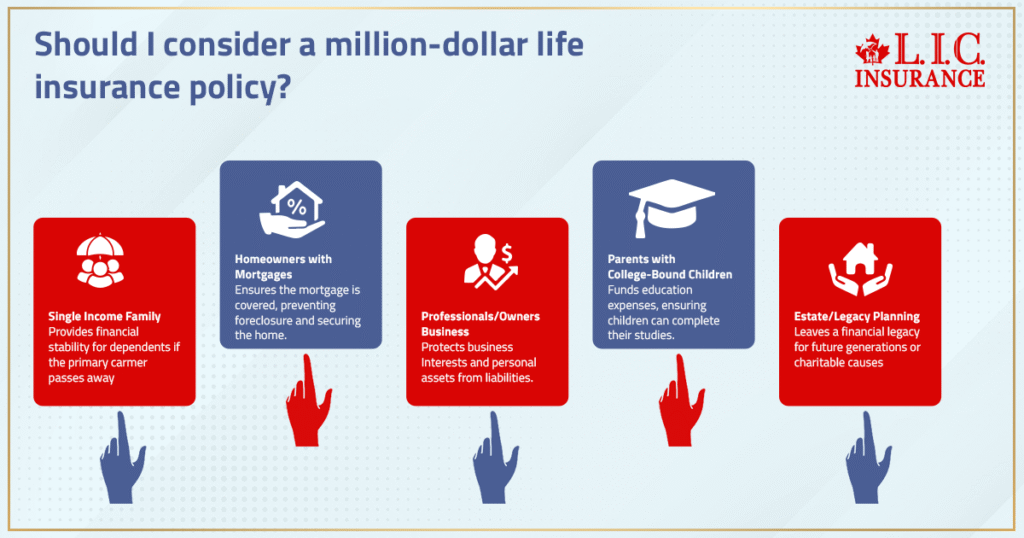
    Financial security isn’t about how much we make; it’s about how well off our family would be if we disappeared tomorrow. It’s why we typically suggest higher coverage levels, especially if you have:

    • Families relying on a single income
    • Homeowners with long-term mortgages
    • Professionals and business owners with significant responsibilities
    • Parents supporting children through post-secondary education
    • Individuals planning to leave behind an estate or charitable legacy

    When life happens unexpectedly, your death benefit becomes the lifeline that keeps everything together. And when that benefit is properly structured—like a Million Dollar Life Insurance Policy—it replaces not just income but the sense of financial independence your loved ones deserve.

    Should I Consider a Million-Dollar Life Insurance Policy

    Understanding The Real Cost Of A Million Dollar Life Insurance Policy

    One of the biggest misconceptions we hear is, “A million-dollar policy must be expensive.” The truth is, it depends on what kind of policy you choose.

    For example:

    Younger, healthy applicants can often secure a Million Dollar Life Insurance Policy at a surprisingly affordable cost, sometimes less than a daily coffee. As brokers, we help our clients compare these structures side by side to ensure they balance cost, coverage, and long-term benefits.

    How Cash Value Works In High-Value Life Insurance

    When we discuss cash value Life Insurance, people don’t often seem to understand that it’s not simply insurance, but an asset. With every premium payment, you build equity inside the policy, growing tax-deferred over time. That also means that you can have access to this cash value during your life — through policy loans, withdrawals or even as collateral for investing in a business!

    For Canadians who are looking to grow and diversify wealth or plan for retirement income, the cash surrender value can serve as a strong safety net. It’s part of why so many professionals choose Whole Life Insurance—because it provides both protection and flexibility, bundled into a single financial plan.

    Cash Value Life Insurance is often used as part of larger strategies we help clients with: tax-free income in retirement, funding future opportunities while maintaining a guaranteed death benefit for your heirs. It’s intelligent, stable and structured for the long haul.

    Balancing Term And Permanent Coverage For Optimal Protection

    You don’t necessarily need the same amount of insurance for all time. It’s often best to take a middle path.

    Often, we construct hybrid strategies — a layer of term Life Insurance for shorter-term needs (say, around your mortgage or dependent years) on top of a base of whole life or universal life to provide lifelong protection. This combination keeps the premiums affordable, while your family is still fully covered in the event of an unforeseen death.

    This method also allows for potential financial planning in the future. As your income expands or loans get paid down, you can convert term coverage to permanent while using the time to build up the cash value aspect. It’s about creating a plan that fits in with your life, rather than against it.

    A Million Dollars: Putting The Number In Perspective

    Let’s talk plain: a million dollars sounds enormous until you get into the weeds.

    If your family spends $80,000 per year, a million-dollar death benefit can replace approximately 12 years of income — and that’s before taking inflation into account. Throw in mortgage payments, taxes, education, and health care, and you begin to understand why it isn’t over the top. It’s essential.

    Most Canadians are unaware that running a household is more expensive than they think. That’s a big reason why I often come back with numbers beyond a million dollars when we figure out how much Life Insurance a family really does need.

    We’re not dream merchants. We protect reality. And that reality costs money. Sufficient Life Insurance means your family won’t have to make impossible decisions in the worst possible circumstances.

    Life Insurance And Business Owners: Beyond Personal Coverage

    For business owners and incorporated professionals, High Value Life Insurance Policies are more than personal protection—they’re a strategic financial tool.

    A Million Dollar Life Insurance Policy can:

    • Secure funds to buy out partners through shareholder agreements
    • Cover corporate loans or key-person risks
    • Provide liquidity for estate or tax obligations
    • Support business continuity for employees and clients

    Incorporated professionals also benefit from cash value accumulation inside corporate-owned whole life policies, which can later support retirement income, succession planning, or even collateralized lending. It’s one of the smartest ways to ensure both your business and your family remain financially stable.

    Financial Planning That Includes Life Insurance

    True financial planning isn’t just about saving or investing—it’s about protecting what you already have. A Life Insurance Policy worth over $1 million integrates seamlessly with your broader wealth strategy.

    Here’s how we often position it for our clients:

    • Estate Planning: A tax-free death benefit ensures assets transfer smoothly without eroding value.
    • Debt Protection: Coverage large enough to settle all liabilities, from mortgages to business loans.
    • Legacy Goals: Funding charitable donations or trusts for future generations.
    • Retirement Supplement: Leveraging cash value for extra cash or tax-advantaged withdrawals.

    Every one of these objectives supports long-term financial protection and financial independence—the pillars of true wealth stability.

    Choosing The Best Life Insurance Plan In Canada

    When it comes to finding the best Life Insurance Plans in Canada, there is no “one-size-fits-all”. It all depends on your goals, your age and your tolerance for risk.

    We begin with a comprehensive needs analysis– examining your financial responsibilities, income, assets, dependents and future goals. Next, we review Life Insurance providers in the industry and find contracts that offer strong insurance protection, consistent cash value growth, and flexible terms.

    We are independent brokers, so we work for you — not for the insurance companies. Whether you’re thinking about whole life, term life or universal life, we ensure your coverage will meet your real-world needs, not some sales quota.

    The Real Question: What Is Your Life Insurance Worth?

    Life Insurance is like that rarefied dusty old Rolling Stones album — something that only gains in value after it’s too late to purchase anymore. Today, the cost of Life Insurance is always cheaper than tomorrow, the regret. So when you want to know “How much Life Insurance should I buy?” —the response should always be commensurate with your income, lifestyle and the dreams you wish to have guarded.

    If you’ve managed to put down roots, create a home and raise your baby — that is life worth something, right? — Then your coverage should reflect that value. And in most Canadian homes, that means a million dollars or more. Because safeguarding your family’s future isn’t simply something you can do—it’s your legacy in action.

    Final Thoughts: Why It’s Time To Think Bigger

    A Million Dollar Life Insurance Policy is not extravagant – It’s just enough coverage. It’s about vision and discipline, and love in the form of money. It’s a whole life policy that offers long-term growth, or a term life layer to cover short-term debts – the Commute in this portfolio is already preparing you for your departure time.” “A permanent policy designed for legacy transfer is no different.

    We understand that with the right plan, everything is possible. Families grieve—but they don’t collapse. The founder is lost to the company, but on their feet. Futures continue, uninterrupted.

    That is the essence of Real Life Insurance Coverage. It preserves your story long after you’ve read the final page.

    Get The Best Insurance Quote From Canadian L.I.C
    Call +1 416-543-9000 to speak to our advisors.
    Get Quote Now

    FAQs

    Professionals frequently have various financial obligations — business loans, family commitments, you name it — that smaller plans simply can’t accommodate. With a $1 million Life Insurance Policy, your earning potential, debts and legacy wishes are 100% secure under the shadow of that one financial rainy day fund.

    Returns on the cash value Life Insurance portion are typically built up over time with some guaranteed interest rates and dividends. It’s also a built-in savings account, and you can access your funds without impacting the death benefit (which is guaranteed), so it becomes an integral part of your long-term financial plan.

    Once the cash surrender value of your Life Insurance Policy is strong, the whole life policy could be a supplement to retirement through tax-efficient access to dollars you’ve saved. This option adds more flexibility: you can use part of your investment while you are alive and simultaneously retain lifetime coverage.

    A good plan centers on purchasing lifetime insurance that can grow and change with your financial situation. It’s intended for Canadians who see Life Insurance as one piece of a larger financial plan that mixes protection, potential cash flow and long-term wealth preservation.

    Yes. Insurance plans are usually flexible to increase your coverage or make changes based on changes in financial responsibilities. Whether you buy more term coverage or beef up your permanent policy, a good insurance company should be able to customize choices that will keep pace with changes in your life and earnings.

    Most of the time, when a Life Insurance claim is filed, the payout will be tax-free for families, allowing them to have access to the lump sum when they need it most. As a result, Million Dollar Life Insurance is one of the most effective tools available for wealth transfer and long-term financial independence.

    Canadians who want comprehensive coverage — for short-term debts and lifelong commitments — are best served. Combining term Life Insurance and whole Life Insurance provides you with low-cost coverage today, with permanently protected financial security for your family’s future.

    Your Life Insurance rate will depend on health, age, policy type and coverage amount. The cost of a Million Dollar Life Insurance Policy can vary a lot, but choosing the right coverage from top Life Insurance companies will guarantee value, security and enough protection for your family’s future.

    Key Takeaways

    • A Million Dollar Life Insurance Policy is not about wealth—it’s about providing real financial security for your family’s future.
    • Rising living costs, education expenses, and long-term debts make higher Life Insurance coverage more necessary than ever for Canadians.
    • Combining term Life Insurance and whole Life Insurance helps balance affordability with lifetime protection and cash value growth.
    • A well-structured Life Insurance Policy can also support financial planning, business continuity, and estate goals.
    • The cash surrender value of permanent Life Insurance creates flexibility, offering access to funds during your lifetime if needed.
    • High-value coverage ensures your death benefit truly replaces income, protects your home, and maintains your family’s financial independence.
    • Working with experienced advisors like Canadian LIC helps you compare Life Insurance companies and choose the best Life Insurance Plans in Canada for your unique situation.

    Sources and Further Reading

    • Canadian Life and Health Insurance Association (CLHIA) – Life Insurance in Canada Fact Book 2024
      Provides national data on coverage amounts, claims paid, and Life Insurance ownership trends among Canadians.
      https://www.clhia.ca 
    • Statistics Canada – Household Debt and Financial Security Reports
      Offers insights on average Canadian debt levels, mortgages, and the financial obligations that drive insurance needs.
      https://www.statcan.gc.ca 
    • Financial Consumer Agency of Canada (FCAC) – Understanding Life Insurance
      A government-backed overview of Life Insurance Policy types, coverage limits, and choosing the right plan for your family.
      https://www.canada.ca/en/financial-consumer-agency.html 
    • Insurance Bureau of Canada (IBC) – Consumer Guide to Life and Health Insurance
      Details how Life Insurance works, policy structures, and claim processes within Canadian regulatory frameworks.
      https://www.ibc.ca 
    • Canadian Institute of Actuaries (CIA) – Research on Longevity and Financial Planning
      Offers data-backed insight on lifespan trends, long-term coverage needs, and mortality risk management.
      https://www.cia-ica.ca 
    • Bank of Canada – Household Finances and Economic Well-being Reports
      Analyzes inflation, debt-to-income ratios, and cost-of-living data relevant to determining adequate Life Insurance coverage.
      https://www.bankofcanada.ca
    • Canada Life Assurance Company – Understanding Whole Life and Permanent Insurance
      Explains the structure and benefits of permanent Life Insurance and its role in long-term financial planning.
      https://www.canadalife.com 

    Feedback Questionnaire:

    Your thoughts help us serve families and professionals across Canada better. Please take a minute to share your experience and challenges below — it only takes a moment but means a lot to us.


      Inside A Million-Dollar Life Insurance Policy: What’s Really Covered And What’s Not

      Inside A Million-Dollar Life Insurance Policy: What’s Really Covered And What’s Not

      Inside A Million-Dollar Life Insurance Policy - What’s Really Covered And What’s Not
      Canadian LIC

      By Pushpinder Puri

      CEO & Founder

      SUMMARY

      A detailed breakdown of what a Million Dollar Life Insurance Policy truly covers, what it doesn’t, and who needs it. Includes insights on policy types, monthly premium ranges, Life Insurance company selection, coverage for college tuition and financial obligations, and how cash value in Whole Life Insurance builds long-term protection. Ideal for Canadians seeking affordable Life Insurance Plans to protect their family’s financial future.

      Introduction

      It may sound like a lot, a million. But when it comes to providing for your family’s financial future, maybe it’s enough. In 2025, as per a report issued, it was noted that the average Canadian family would need to have at least $850,000 in Life Insurance to cover outstanding debts and provide for mortgage, university funding and future costs if the major earner died. And yet, many Canadians are underinsured, still questioning if a million-dollar Life Insurance Policy is overkill or necessary.

      Here, the same scenario plays out every single day: Families that don’t know what a Million Dollar Insurance Policy actually includes, how much insurance costs and whether or not it is even right for them. So here’s the inside scoop on what a Million Dollar Policy actually is — and what it covers (and doesn’t) and who actually needs it.

      How Much Life Insurance Does A Family Really Need?

      Let’s dissect how much Life Insurance is enough. You generally want a cushion of 10 to 15 times your annual salary. So if you make $80,000 a year, you’ve already got yourself into that range of needing $800,000 to $1.2 million in Life Insurance. That rule of thumb applies to more than just end-of-life expenses — it protects income replacement, mortgage payments, debts that are not yet repaid and your children’s college tuition.

      Million Dollar Life Insurance Plans are available for this situation.

      What Life Insurance Policies Qualify For A Million Dollar Benefit?

      There isn’t one type of Life Policy that fits everyone. You can choose between Term Life Coverage, Whole Life Insurance, or Universal Life, depending on your budget and goals. Here’s the lowdown:

      • Term Life: More affordable compared to permanent policies. You lock in a monthly premium for a specific term length (10, 20, or 30 years). It’s ideal for temporary needs like raising children or paying off a mortgage.
      • Whole Life Insurance: Comes with a cash value component and offers lifetime coverage. This makes it perfect for estate planning and leaving behind a lasting death benefit.
      • Universal Life: A flexible policy with adjustable premiums and death benefit options, often used in more advanced financial protection strategies.

      Each can be structured as a Million Dollar Policy, depending on the insurer and your health status, age, and financial obligations.

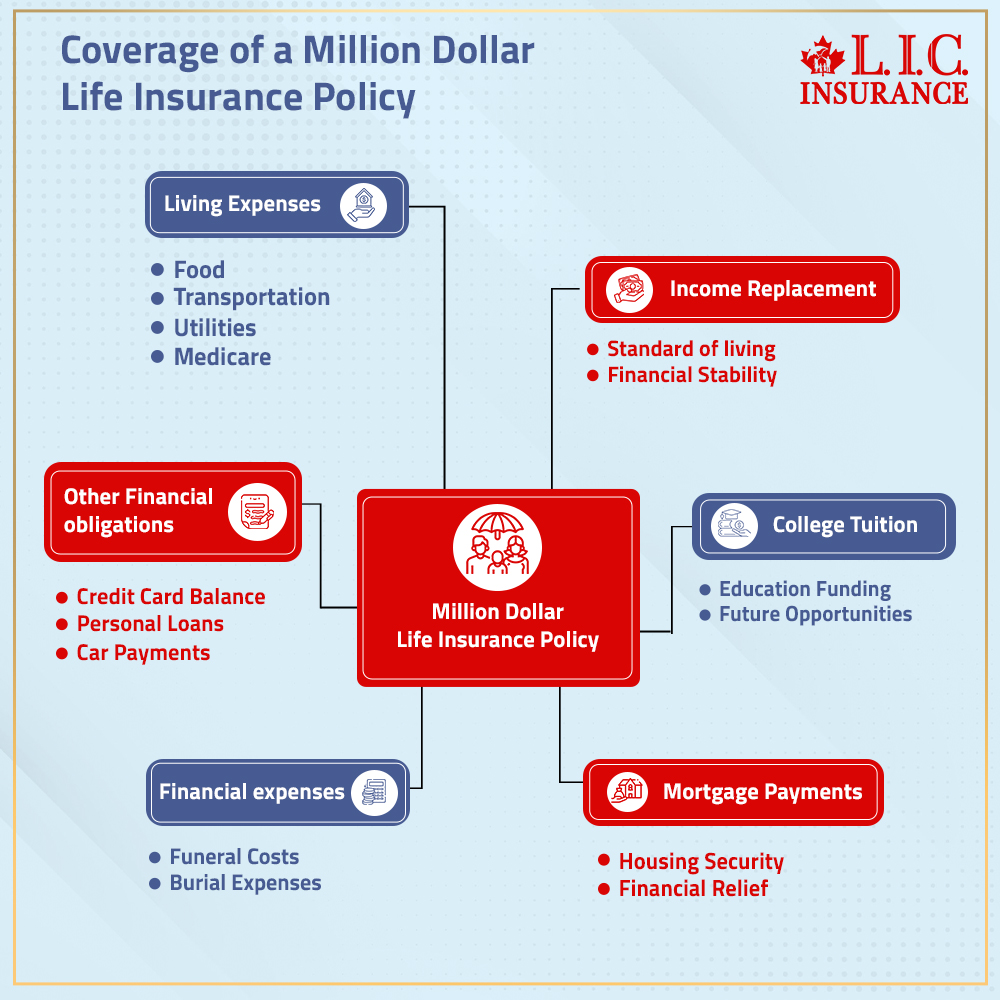
      What Does a Million Dollar Insurance Policy Cover?

      Here’s what a typical Million Dollar Life Insurance Policy provides coverage for:

      • Income replacement needs: Your loved ones can maintain the same standard of living.
      • College tuition: $80K-$120K per child over 4 years.
      • Mortgage payments: The average Canadian mortgage in 2025 is over $370,000.
      • Final expense: Funeral and burial costs can range from $7,000 to $15,000.
      • Other financial obligations: Credit card balances, personal loans, car payments.
      • Living expenses: Food, transportation, utilities, and medical care.
      Coverage of a Million Dollar Life Insurance Policy

      What A Million Dollar Insurance Policy Does Not Cover

      Yes, there are limits. Your insurance company may deny claims under the following conditions:

      • Pre-existing medical conditions were not disclosed during the application.
      • Death during a contestability period (usually within two years).
      • Suicide within the policy’s first two years.
      • Fraud or false information during the underwriting process.

      So it’s vital to work with a reputable Life Insurance company and disclose everything honestly.

      Million Dollar Life Insurance Policy Costs: The Actual Price You Pay

      So, what are the real Million Dollar Life Insurance Policy costs?

      It depends on several factors: your age, health history, smoking status, the type of policy, and term length. Here’s a rough idea for healthy, non-smoking individuals in 2025:

      • 30-Year-Old Male:
        • Term Policy: ~$35/month
        • Whole Life: ~$750/month
      • 40-Year-Old Female:
        • Term Policy: ~$50/month
        • Whole Life: ~$1,050/month

      So yes, a Million Dollar Policy can be surprisingly affordable—especially if you’re young and in good health.

      Choosing The Right Insurance Company Matters

      Not all insurance companies are built equal. We only work with providers that have a long history of financial strength and reliable death benefit payouts.

      Look for insurers that:

      • Have at least an A rating from agencies like A.M. Best or DBRS
      • Offer strong support for claims
      • Provide digital tools for policy management
      • They are known for transparency in underwriting

      How A Million Dollar Policy Depends On Your Lifestyle

      You might think one million dollars is overkill. But take a moment to add up your family’s projected future expenses, existing debts, and income replacement needs. Suddenly, a Million Dollar Life doesn’t seem too much – it seems just right.

      This is especially true if:

      • You’re the sole or primary earner
      • You have children or dependents
      • You have a large mortgage or other expenses
      • You want to leave behind financial security and cover all financial obligations

      Even women tend to underestimate their value when it comes to protecting their family’s financial future. The truth? Whether you’re the breadwinner or managing the household, Life Insurance Policies make a difference.

      How Permanent Coverage Helps You Stay Financially Secure

      If you require life-long insurance coverage, a Whole Life Insurance Policy is your option. It accumulates cash value, which you can borrow against in the future (for emergencies, college costs and even for supplementing retirement income).

      Here’s one way of looking at it: with whole life, you’re not only protecting your family with a death benefit — you’re also growing an asset.

      And if you choose a million dollars of coverage, that cash value aspect becomes more and more potent over time.

      The Underwriting Process: What You Should Expect

      When you apply for a Million Dollar Term Policy or permanent plan, you’ll go through the underwriting process, which includes:

      • A medical exam
      • Review of your medical records
      • Lifestyle questionnaire
      • Financial review (to confirm how much coverage makes sense)

      It’s not as intimidating as it sounds, and our advisors make it easy.

      What Makes Life Insurance Affordable In Canada Today?

      We live in a competitive market where affordable Life Insurance Plans in Canada are now more accessible than ever. Whether you choose Term Insurance or Whole Life, you can often get high-dollar Life Insurance coverage at an affordable price.

      Factors that help lower your monthly premium:

      • Applying young
      • No tobacco use
      • Clean driving record
      • Good physical health

      We’ll walk you through every option to find the right fit — from Term Life Insurance rates to the best-value Life Insurance Policies for your needs.

      Final Expense And Beyond: Thinking Long-Term

      Final expense insurance is often mistaken for more valuable policies by many Canadians. The truth? Million Dollar Life Insurance Plan does both. It provides for final expense and then some — real financial help for decades.

      Do not leave your circle hustling. If they turn toward the challenge when their time comes, and do it from a position of financial security rather than financial desperation, we will all be better off.

      Conclusion: Is A Million Dollar Life Insurance Policy Worth It?

      Absolutely. If you are getting a Million Dollar Policy and want to make sure your family is well taken care of, all bills are accounted for when the unfortunate happens and that they live comfortably without worry, then absolutely, a Million Dollar Policy more than makes sense.

      We assist Canadians daily to figure out how much coverage you’ll need, know the true monthly cost and get insured via trusted insurance companies.

      We are not here to sell you more than you need — we’re here to help you get covered, with the right Life Insurance product for your situation. Because you know what coverage may be?

      Get The Best Insurance Quote From Canadian L.I.C
      Call +1 416-543-9000 to speak to our advisors.
      Get Quote Now

      FAQs

      Your monthly premium could go up for a number of reasons, such as your age, the riskiness of your occupation, family health history or lifestyle habits, like using tobacco or consuming alcohol. Certain Life Insurance carriers may also increase rates if you have low or unstable income when applying for a Million Dollar Life Insurance Policy.

      There are Life Insurance Policies with non-medical underwriting available, but these types of plans generally carry higher premiums and lower coverage approval. Most insurance companies will still require a detailed medical exam and a very full disclosure for complete dollar Life Insurance Policy coverage, like one for a million dollars.

      Yes, the option for conversion is a standard for most term life policies. You can convert to Whole Life Insurance or Universal Life without another medical exam. This means that you can lock in lifetime protection or accumulate savings while keeping the health rating status you started out with.

      Absolutely. For business owners, Million Dollar Life Insurance Policies are commonly used for income replacement, buy-sell agreements and loans. The Life Insurance company payout provides a cushion with which to continue your business and also protects your family’s financial future & other financial liabilities.

      Yes. A good number of families apply a portion of their death benefit from a Million Dollar Policy to fund future tuition. As tuition continues to soar in Canada, this type of Life Insurance guarantees your child’s education is never disrupted, at least for financial reasons, should you not be around to carry it through.

      Your income, age, health status and existing financial obligations will determine your eligibility. Many Life Insurance companies will consider your lifestyle, the risk associated with your occupation, and whether you can afford to pay the premiums. We assist clients in determining how to calculate what they can afford while still being realistic.

      Although missing monthly premiums can lead to a grace period, typically 30 days, failure to make the payment on time could cause your Life Policy to lapse, and you would lose your Life Insurance coverage. A few whole life or Universal Life policies have sufficient cash values to keep the policy in force for a period of time.

      Surprisingly, yes. Term Life Insurance rates get cheaper the younger you are. Many young professionals secure cheap Life Insurance Plans in Canada relatively early to safeguard future dependents, manage student debt and provide financial stability for the long term.

      Definitely, a $1m life cover assists in paying off substantial debts such as car loans, credit card debts and mortgage pay-outs. It’s designed to alleviate financial pressure, enabling your family to retain assets and cover other costs without undue tension.

      Yes. Most Life Insurance Policies offer optional riders such as critical illness, disability waiver of premium or children’s protection. These riders lapse, and you lose the cost of premiums if it is not formed by age 100 (and will be harder to form as insurers adjust pricing with changes in interest rates) – but they give added dollar Life Insurance protection against unforeseen health or income events.

      It will be wise to answer, depending on the client’s purpose. Whole life yields cash value and life coverage, but it is costly. On the contrary, term insurance is cheaper than a permanent policy, but difficult to afford after the end of the term. We, financial advisors, rely on our clients’ scheduling and income to recommend the best policy.

      Key Takeaways

      • A Million Dollar Life Insurance Policy is not excessive — it’s often the baseline needed to protect a family’s financial future in Canada.

      • Policy types like Term Life, Whole Life Insurance, and Universal Life can all be structured to offer Million Dollar Coverage based on your budget and needs.

      • Coverage typically includes income replacement, college tuition, mortgage payments, final expense, and other financial obligations.

      • Pre-existing medical conditions, fraud, or omissions during the underwriting process can void a claim — full disclosure is key.

      • Million Dollar Life Insurance Policy costs can be surprisingly affordable, especially for younger, healthy Canadians seeking affordable Life Insurance Plans.

      • The right Life Insurance company can make all the difference in payout speed, claim support, and long-term policy management.

      • Choosing Permanent Coverage (like Whole Life) provides a growing cash value component, useful for future emergencies or tax-smart withdrawals.

      • Clients often discover that a Million Dollar Policy isn’t about luxury — it’s about love, security, and protecting what truly matters.

      Sources and Further Reading

      Government of Canada – Life Insurance Overview
      https://www.canada.ca/en/financial-consumer-agency/services/insurance/life-insurance.htm l
      → Offers an unbiased explanation of Life Insurance types and considerations for Canadians.

      Canadian Life and Health Insurance Association (CLHIA)
      https://www.clhia.ca/web/clhia_lp4w_lnd_webstation.nsf/page/ConsumerInformation
      → Industry-backed resource outlining how policies work and what to expect from insurers.

      Insurance Bureau of Canada – Life Insurance Basics
      https://www.ibc.ca/on/business/insurance/life-insurance
      → Explains coverage options, underwriting, and choosing the right Life Insurance company.

      Sun Life – How Much Life Insurance Do I Need?
      https://www.sunlife.ca/en/tools-and-resources/money-and-finances/life-insurance/how-much-life-insurance-do-i-need/
      → Practical calculator and guidance tailored to Canadian income and expense levels.

      Manulife – Understanding Term vs Whole Life Insurance
      https://www.manulife.ca/personal/insurance/life-insurance.html
      → Offers real-world examples of term life coverage, cash value, and monthly premiums.

      Canada Life – Planning Your Insurance Needs
      https://www.canadalife.com/insurance/life-insurance.html
      → Reviews differences between term length, permanent coverage, and how to assess financial obligations.

      Feedback Questionnaire:

      Your feedback helps us serve Canadian families better. This won’t take more than 2 minutes.


        How to Buy a Million Dollar Life Insurance Policy?

        It’s just one of the ordinary days when you are sitting at your desk, and the light of your computer screen hardly lights the whole room up. You are just done with a long day’s work, and your thoughts drift toward the family.

        How to Buy a Million Dollar Life Insurance Policy?

        By Canadian LIC, March 25, 2024, 12 Minutes

        How to Buy a Million Dollar Life Insurance Policy

        It’s just one of the ordinary days when you are sitting at your desk, and the light of your computer screen hardly lights up the whole room. You are just done with a long day’s work, and your thoughts drift toward the family.

        Then it hits you, and it is a hard-hitting thought: what if something happens to me? Will it be good for all? Will they survive without the money you earn? These are questions that most of us have in our minds, but not all take the step to secure the future of their family. This is where a million-dollar insurance policy comes in—the one thing that sounds terrifying but is a necessity for many.

        If monthly payments for Million Dollar Life Insurance Policies sound like something very difficult to you, you’d be perfectly right. Many find themselves lost within the terminology and numbers, not understanding fully what they are doing.

        This blog sets out to take some of the mystery out of everything that needs to be known about securing a Million Dollar Life Insurance Policy in simple, actionable steps. It’s going to be a journey together from confusion to clarity, from anxiety to assurance.

        That’s where a life insurance Million Dollar Policy becomes more than just a safety net—it becomes a foundation for financial confidence. Whether you’re protecting your income, your children’s future, or ensuring your family isn’t burdened with debt, a Million Dollar Policy life insurance plan can make a meaningful difference. Contrary to what many believe, Million Dollar Life Insurance is not just for the wealthy—it’s for anyone who wants lasting financial security. As more Canadians realize the value of Million Dollar Insurance Policies, the demand for clear, practical guidance has never been higher. This guide is here to simplify the path to securing Million Dollar Life Insurance Policies with clarity and confidence.

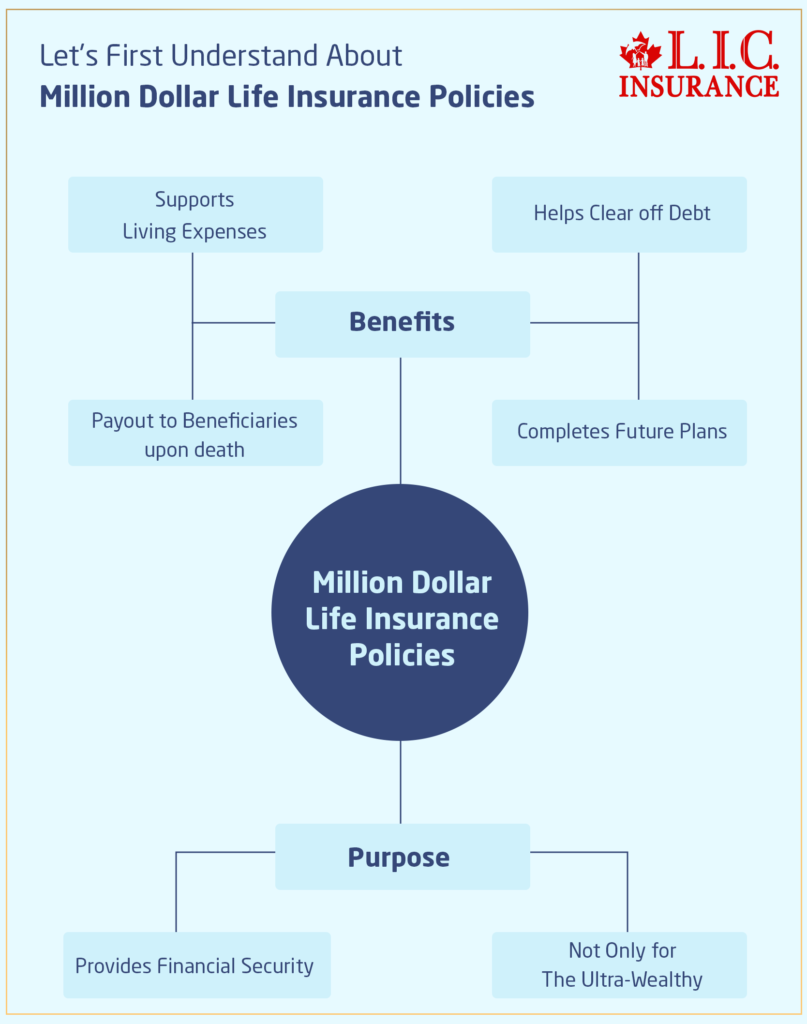
        Let's First Understand About Million Dollar Life Insurance Policies

        Understand About Million Dollar Life Insurance Policies

        A Million Dollar Life Insurance Policy isn’t just for the ultra-wealthy; it’s a practical choice for anyone looking to provide a high level of financial security for their family. This policy is quite simple in the sense that, in case of death, there is a payout to the beneficiaries, which may be of help to meet their living expenses, clear off some debt, or complete the future plans you have.

        Step 1: Assessing Your Need

        The first question would be to ask: Does one really need a million-dollar policy? The answer then shall lie with due consideration towards one’s financial status and a well-planned future need for the family. Consider present income, debts, and probable family expenses in the future.

        As a thumb rule, multiply your annual income by ten, and that is the policy one should seek. However, a person who is burdened with loans and a few specific future financial obligations, like children’s college expenses, marriage, etc., may need to adjust this figure downwards.

        Step 2: Understanding the Types of Life Insurance Coverage

        Before we understand how to buy Million Dollar Insurance Policy, let’s first make clear the basic kinds of life insurance: Term Life Insurance and Whole Life Insurance. 

        Term Life Insurance, on the other hand, is designed to pay out if you die within the period that you’ve agreed to be protected for—generally known as the Term Policies, include cover for anything from 10 to 30 years and are simple and cheaper forms of life insurance. Hence, many take it. Whole Life Policies, in contrast, protect a person for their entire life, hold cash value, and demand higher monthly costs.

        Real-Life Tip: How Financial Institutions View a Life Insurance Million Dollar Policy — And How It Can Be Used as Leverage

        One of the least-discussed yet incredibly valuable uses of a Million Dollar Life Insurance Policy is its role as a financial asset when structured strategically. Many people assume that Million Dollar Life Insurance Policies are only about providing for loved ones in case of death. However, when properly designed, particularly with Permanent Life Insurance options, they can serve as tools to access liquidity, enhance creditworthiness, or even support business financing.

        Financial institutions often view Million Dollar Insurance Policies with built-in cash value (such as whole or universal life) as collateral for loans. This can be particularly advantageous if you’re a business owner or investor seeking leverage without liquidating other long-term assets. When applying for a line of credit or commercial loan, a Million Dollar Policy life insurance document showing accumulated cash value can weigh heavily in your favour.

        This adds another layer of practicality and value to securing a Million Dollar Life Insurance plan, not just as a safety net but as a dynamic financial instrument. Whether you’re planning for legacy, liquidity, or leverage, well-structured Million Dollar Life Insurance Policies offer far more than death benefit protection—they can become part of your active wealth strategy.

        Step 3: Getting Quotes

        Now, what could be done in the practical term? Starting with the insurance, an individual could get a quote from several insurance companies. This will give you a rough idea on what’s the monthly payment for 1 million life insurance.

        And don’t let the numbers scare you off. The premiums in Term Life Insurance are usually really affordable. Use online calculators as a guide, and talk with insurance agents to get a good idea of the potential premium levels.

        Step 4: Evaluating Your Health

        Your health usually determines the premium you pay for insurance. Generally, the healthier you are, the lower the premium you will have to pay. But do not worry—there are a lot of policies for those not in the best of health. Be honest in your health assessment to avoid any complications with your policy down the line.

        Step 5: Choosing the Right Term

        When you decide on a term for your Term Life Insurance Policy, select a term length that will come closest to your most significant financial obligations. For example, if you are 30 years from retirement and will have other financial arrangements for your family by then, then this would be ideal.

        Step 6: Completing the Application Process

        You fill out papers, and you might also undergo a medical exam. An insurance company uses them to decide how much of a risk you are to them and what your premium is going to be. This process is not the same for everyone, so it’s better to stay prepared in advance.

        Step 7: Designating Your Beneficiaries

        The most important decision is who you want your beneficiaries to be. These are the persons or parties who will receive the insurance payout in case you die. Consider carefully, though, who may most need the funds or would be tasked with administering the estate for you.

        Find Out: How is a Million Dollar Life Insurance Policy Paid Out?

        Find Out: Is it possible to have a Million Dollar Life Insurance Policy?

        Overcoming Common Struggles

        Sometimes, getting started on the search for a million life insurance policies can look like jargon, numbers, and decisions that appear daunting at first glance. But with simplification, consulting experts, and keeping our eyes on the insurance quotes, an assured future for loved ones, we surely can pass these hurdles very easily.

        Tackling Language Barriers: The insurance industry uses a bit of complex terminology. However, understanding the specifics of a Million Dollar Insurance Policy and the monthly payment for a million life insurance policies doesn’t have to be a barrier.

        Many insurance companies now offer resources in multiple languages, and some agents specialize in serving diverse communities. Feel free to ask for materials in your first language or for an interpreter if it helps. Remember, clarity is key in these discussions, and it’s important that you fully understand the policy you are considering.

        Demystifying Financial Terms: Going alone, some of the terminologies like “premiums,” “beneficiaries,” or “death benefit” might be speaking a foreign language. To do away with some of the mysteries these terms hold, demystify them for the client: a premium is just the monthly payment that you make to keep your insurance policy active. Let’s talk about the monthly premium or average monthly costs of such a Million Dollar Life Insurance Policy. We are talking about the amount that you have to budget to keep this safety net for your family every month. In the form of online resources, brochures, and meeting with the insurance agents face to face, the best means to build your understanding. Remember, no question is too small or silly to ask.

        Addressing the Fear of High Premiums: Most have common worries—a Million Dollar Insurance Policy sounds like it would be expensive to secure. It’s a valid worry, definitely, because not too many people take such financial commitments lightly. What may surprise you, however, is that the monthly million life insurance policy payment may actually be friendlier to your pocket than you’ve always thought.

        Your age, health, and lifestyle, as well as the length of the term of the policy, will all matter to the policy and will give definition to the key amount of premiums you are to pay. For example, healthier, younger people tend to have lower rates. Shopping around with different providers of insurance, comparing quotes, and asking lots of questions may help you find a policy that will work with your budget and at least secure some financial protection for your family.

        Seeking Professional Advice: A range of life insurance includes help from an agent or financial advisor of an insurance company. An insurance company’s agent or financial advisor can help cut through the jargon, compare policies, and give a clear picture of what kind of insurance would best fit the need and budget.

        They can offer individual consultation on approaches that will ensure the needed coverage and further dictate guidelines to follow in making the monthly payment for the Million Dollar Life Insurance Policy bearable. Do not hesitate to consult with professionals. It’s their job to assist you in securing the best possible coverage for your situation.

        Focusing on the Goal: If during the process at any time you find the task daunting in front of you, remind yourself again why you were even considering getting a Million Dollar Insurance Policy in the first place; it’s all about mental peace and satisfaction, security, and your loved ones.

        Keeping that perspective can help you get encouraged to push through the complexities and find an arrangement that ensures, in a very literal sense, that your family’s future is taken care of, no matter what.

        By addressing these common struggles with practical steps and a focus on the ultimate goal, securing a Million Dollar Insurance Policy becomes not just a possibility but a clear path forward. Remember, the journey to protect your family’s future starts with understanding, planning, and action. Let’s take that step today, all of us together.

        Get The Best Insurance Quote From Canadian L.I.C

        Call 1 844-542-4678 to speak to our advisors.

        Canadianlic best insurance quote

        To Wrap Up

        While this might sound rather daunting—having to secure a Million Dollar Life Insurance Policy, believe it or not, it is definitely manageable and in fact, a very responsible move on your part to ensure that your family’s future financial security has been well taken care of, even long after you are gone.

        And remember, the best time to buy life insurance coverage is now. Your future self—and definitely, your family—will be most grateful. Never let uncertainties hold you back. Start your journey to financial security today, knowing you have taken a significant step by taking care of your loved ones.

        Get The Best Insurance Quote From Canadian L.I.C

        Call 1 844-542-4678 to speak to our advisors.

        FAQs Related to Buying a Million Dollar Life Insurance Policy

        A Million Dollar Insurance Policy is ideal for a person who wants to ensure family financial security in case he is not around. Suppose your annual income, debts, and even future financial obligations, or paying off a mortgage, suggests your family would need significant financial support, this policy might be right for you.

        Yes, the monthly payment for a million life insurance policy can be surprisingly affordable, especially if you opt for a Term Life Insurance Policy and are in good health. Premiums vary by many determinants, including age, health status, and more; hence, it would be important to get quotes from different insurers and compare policy options.

        Normally, you must attach identification and financial information that will show your income and assets, with medical records. In addition, the insurer can request a medical exam that will reveal the state of your health.

        But then again, you would still be eligible for the one-Million Dollar Life Insurance Policy even if you have a pre-existing medical condition, with some considerations, of course, on premium rates. They might then try and assess the health risks in your health and recommend paying a higher premium or taking another life product.

        Lengths of approval time can largely vary by the insurer, your health at the time of application, and whether a medical exam is required or not. It usually takes anywhere from a few days to several weeks. Obtain faster approval times with policies that feature simplified underwriting.

        Yes, many insurance companies allow coverage to increase, but they are subject to further underwriting. Suppose your financial standings are different from before, and a greater coverage amount is felt to be needed. In that case, contact your insurer and consult the opportunity to increase policy coverage.

        Some insurers have a grace period during which the payment can be done without losing the coverage if one misses the payment date. Failure to make the payment within the stipulated number of days of grace would subject your policy to lapse, hence leaving you without coverage.

        You can cancel at any time. Really, if it is a Term Life Insurance Policy, then all you would have to do is stop paying the premiums, and, therefore, the coverage would stop. If you have a whole-life policy, you might receive a cash value if you cancel, depending on the terms of your policy.

        Companies selected should have strong financial stability, positive customer reviews, and rates for premiums that could reasonably compete. It would be prudent on your part to choose such a life insurance company that offers the type of policy most suitable for your requirements and holds a reputation for excellent customer service.

        You can have several life insurance policies from various insurers or from one insurer; it will depend on the number of policies that a person can own. Your income and financial holding can accommodate an amount justifiably convertible for total coverage. This strategy can also help as a means of tailoring coverage to certain needs or goals.

        Other factors to be considered in the computation of premiums include your age, the current state of health, and lifestyle choices such as smoking and indulging in dangerous activities. It is critical to the type of policy chosen in making the determination of the amount, together with the term length for Term Life Insurance Policy. The amount of money is used to determine the amount of risk in insuring you.

        Term Life Insurance Policy is a type of policy that includes a specific period of time in which, by paying premiums, a death benefit is offered to the nominee if the insured dies within the said term. It is usually cheap and offers no cash value. On the other hand, Whole Life Insurance, as the name suggests, does cover one’s entire life and comes with a death benefit, including cash value or investment that can be borrowed against or withdrawn under certain conditions, although at higher premiums.

        Most of the time, the death benefit from a life insurance policy, such as a million-dollar policy, beneficiaries receive is untaxed. However, if you have a whole life policy with a cash value component, there might be tax implications if you withdraw or borrow against the cash value. It’s advisable to consult with a tax professional for specific advice.

        Some insurers do offer “no medical exam” policies, even for amounts up to a million dollars, but such policies may have the premium rates significantly above average. These are generally applicable to people below 50 years of age or good health. One should look carefully into comparing these policies, the cost, and the setup of coverage limits.

        Life events such as marriage, having children, or getting a windfall of money in a substantial raise in your financial status should push you to re-evaluate your needs for life insurance. Many policies offer adjustability, where you can upgrade either the amount of your policy or change a term policy into a full life policy. If you are concerned with such aspects, ask your insurer about it.

        Compare rates, look beyond the monthly payment for Million Dollar Life Insurance, and delve deeper into what coverage is included, policy exclusions, and the financial strength and customer service reputation of the insurer. You can work with an insurance agent or a financial advisor who can help you review your options based on your needs and financial goals.

        Once issued, the life insurance policy is rarely, if ever, cancelable by the insurance company as long as the premium is paid. But, of course, the applicant must be honest, and the policy will be void if one misrepresents or omits facts.

        If the premiums are too high to afford, that should engage the insurer in discussion; maybe the terms of the policy could be reshaped or the type of policy changed, or maybe means of cutting the size of the premium down without substantially reducing the coverage found.

        The policyholder may be anybody else, either a spouse or a business partner. With the consent of the other person, any person may take out life insurance covering the life of any other person for whom he has an insurable interest. The insured person must participate in the application process, including any required medical exams.

        Keep the policy documents safe, and let the people you trust know the details of the million dollar coverage, including where the people described as the beneficiaries can find it and how to claim it. You should also, from time to time, review the policy itself and the beneficiary to be sure it accounts for your current desires and state of life.

        Sources and Further Reading

        To deepen your understanding of securing a million-dollar life insurance policy and managing it effectively, consider exploring the following resources. These sources offer comprehensive insights into life insurance, guiding you through the process, clarifying terms, and helping you make informed decisions:

        Life Insurance Guide by the National Association of Insurance Commissioners (NAIC)

        “Life Insurance Basics” by the Insurance Information Institute (III)

        “How to Shop for Life Insurance” by Consumer Reports

        “Life Insurance Buyer’s Guide” by the American Council of Life Insurers (ACLI)

        Further Reading:

        “The Total Money Makeover” by Dave Ramsey

        “Questions and Answers on Life Insurance” by Anthony Steuer

        “Life Insurance, 10th Edition” by Kenneth Black Jr. and Harold D. Skipper Jr.

        Online Forums and Community Groups

        By consulting these sources and further reading materials, you can gain a solid foundation of knowledge on life insurance policies, including the nuances of a million-dollar life insurance policy. Whether you’re a novice or somewhat familiar with the topic, these resources will equip you with the information needed to navigate the life insurance purchasing process confidently.

        Key Takeaways

        Your Feedback Is Very Important To Us

        We appreciate your time in reading our blog about purchasing a million-dollar life insurance policy. To better understand your struggles and how effectively our information has helped you, we kindly ask you to fill out this brief questionnaire. Your feedback is invaluable in helping us improve our content and services.

          1. Personal Details

          Full Name:


          2. Feedback Questions


          The above information is only meant to be informative. It comes from Canadian LIC’s own opinions, which can change at any time. This material is not meant to be financial or legal advice, and it should not be interpreted as such. If someone decides to act on the information on this page, Canadian LIC is not responsible for what happens. Every attempt is made to provide accurate and up-to-date information on Canadian LIC. Some of the terms, conditions, limitations, exclusions, termination, and other parts of the policies mentioned above may not be included, which may be important to the policy choice. For full details, please refer to the actual policy documents. If there is any disagreement, the language in the actual policy documents will be used. All rights reserved.

          Please let us know if there is anything that should be updated, removed, or corrected from this article. Send an email to Contact@canadianlic.com or Info@canadianlic.com

          The Basics of International Student Insurance Plans

          “Life Insurance, 10th Edition” by Kenneth Black Jr. and Harold D. Skipper Jr.

          Sources and Further Reading

          How Much Is a Million Dollar Policy a Month?

          Many of us avoid thinking about the future, particularly when it comes to our absence from it. Still, we have to think about it, especially when it comes to making sure our loved ones are taken care of financially. This is where the idea of a Million Dollar Life Insurance Policy comes in handy. Million dollars may sound like a number that only the rich have, but it’s actually a number that could give your family the means to survive after you die. But how much does an insurance that covers so much cost every month? We’ll get into the specifics of a million-dollar policy insurance quote in this blog. We’ll reveal the factors that affect the price and use real-life examples to help you understand what a Million Dollar Life Insurance Policy might mean for you.

          How Much Is a Million Dollar Policy a Month?

          By Canadian LIC, March 4, 2024, 9 Minutes

          How Much Is a Million Dollar Policy a Month?

          Many of us avoid thinking about the future, particularly when it comes to our absence from it. Still, we have to think about it, especially when it comes to making sure our loved ones are taken care of financially. This is where the idea of a Million Dollar Life Insurance Policy comes in handy. Million dollars may sound like a number that only the rich have, but it’s actually a number that could give your family the means to survive after you die. But how much does an insurance that covers so much cost every month? We’ll get into the specifics of a million-dollar policy insurance quote in this blog. We’ll reveal the factors that affect the price and use real-life examples to help you understand what a Million Dollar Life Insurance Policy might mean for you.

          Understanding the Cost of a Million Dollar Policy

          It might seem complicated to understand how to get a Million Dollar Life Insurance Policy, but it’s easier than you think. To get through this process easily, you need to know what affects your monthly premium and how to talk to Life Insurance companies clearly about your wants and situation. Let’s take a closer look at how to get an accurate Million Dollar Policy Insurance Quote using real-life scenarios as examples.

          Step-by-Step Guide to Getting Your Quote

          Gather Your Information: Before you start, compile details about your age, health condition, lifestyle habits (such as smoking or alcohol consumption), and financial situation. This information will form the basis of your insurance quote. Use Online Tools: Many insurers offer online calculators that provide a preliminary estimate of your monthly premium. While these tools are helpful in getting a ballpark figure, they may not capture all the nuances of your personal situation. Consult with an Insurance Agent: Schedule a consultation with an insurance agent for the most accurate quote. They will consider your specific circumstances and guide you through the available policy options, ensuring you get a tailored quote that reflects your needs.

          Reflect on Your Own Scenario

          Think about your unique situation. Consider your age, health, and lifestyle:

          Age: Remember, younger applicants typically receive lower quotes.

          Health Status: Would you describe your health as excellent, average, or below average?

          Lifestyle Choices: Do you have habits that could affect your quote, like smoking or engaging in high-risk activities?

          Actionable Steps for You

          Self-Assessment: Conduct an honest assessment of your health and lifestyle. This will prepare you for the questions insurers will ask and help you understand the potential impact on your premiums. Research: Use online tools to get a rough estimate of your potential premium. This will give you a baseline understanding of what you might expect to pay. Consultation: Reach out to an insurance agent to discuss your needs in detail. Be open about your lifestyle and health to ensure the quote you receive is as accurate as possible. Comparison Shop: Don’t settle for the first quote you receive. Get quotes from multiple insurers to ensure you get the best coverage at the most competitive rate.

          Conclusion: The Time to Act Is Now

          Getting a Million Dollar Life Insurance Policy may seem like a big deal, but it’s something you can do right now to protect your family’s future. Since the cost depends on a lot of factors, it’s important to look into your choices as soon as possible. Knowing that your family will be able to afford things gives you a lot of ease mentally. If you want to feel safe, don’t wait until it’s too late to think about getting Life Insurance Coverage. Do something right away—start by getting a quote—to protect your family’s financial future.

          Don’t forget that life is uncertain, but your family’s finances don’t have to be. Million-dollar Life Insurance coverage is more than just a number; it’s a way to protect your family and friends from the unknowns of life. Make the decision today to explore your options. It is worth it for your family’s future.

          Find Out: How a Million Dollar Life Insurance Policy Paid Out?

          Find Out: Is it possible to have a Million Dollar Life Insurance Policy?

          Get The Best Insurance Quote From Canadian L.I.C

          Call 1 844-542-4678 to speak to our advisors.

          Canadianlic best insurance quote

          Faq's

          A Million Dollar Life Insurance Policy is a contract between you and an insurance company that promises to pay your beneficiaries a sum of one million dollars upon your death in exchange for regular premium payments.

          Individuals who have significant financial responsibilities, such as supporting a family, paying off a mortgage, or covering future educational expenses, might consider a Million Dollar Policy to ensure their loved ones are financially secure in their absence.

          Affordability varies widely among individuals. Younger, healthier individuals and non-smokers typically receive lower quotes. Utilize online calculators and consult with insurance agents to get a precise quote based on your personal situation.

          You’ll need to provide personal identification, medical records, a detailed health questionnaire, and possibly undergo a medical exam. Some insurers might also request financial documents to prove the policy is appropriate for your financial situation.

          The approval time can vary from a few days to several weeks, depending on the insurance company and whether a medical exam is required. Completing all the necessary documents and medical exams promptly can expedite the process.

          Not always. Some insurers offer no-exam Life Insurance policies, but these might come with higher premiums. Typically, a medical exam provides the insurer with a comprehensive understanding of your health, potentially leading to lower premiums.

          Yes, many policies allow you to increase your coverage, subject to approval by the insurer. This usually requires a reassessment of your health and financial situation.

          Failing to pay premiums can lead to your policy being cancelled. However, most insurers offer a grace period for late payments. Communication with your insurer is essential if you’re facing financial difficulties.

          No, premiums paid on personal Life Insurance policies are not tax-deductible. However, the death benefit received by your beneficiaries is typically tax-free.

          Yes, you can cancel your policy at any time. If you have a term policy, you might not receive any return on the premiums you’ve paid. With permanent policies, you might receive a cash value, depending on the terms of your policy.

          Research and compare different insurers based on their financial strength ratings, customer service reviews, policy offerings, and premium quotes. Consulting with an independent insurance agent can also provide valuable insights tailored to your needs.

          To obtain a Million Dollar Policy Insurance quote, gather your personal and medical information. Then, use online tools provided by Life Insurance companies for a preliminary estimate or contact an insurance agent directly for a more detailed and accurate quote based on your specific circumstances.

          Before applying for a Life Insurance policy worth a million dollars, consider your current financial obligations, the future needs of your dependents, and your overall financial goals. Assessing your health, lifestyle, and the potential impact on your premium rates is also necessary. Finally, think about the term length that best suits your family’s needs.

          Your age is a significant factor in determining the cost of a Life Insurance policy for a million dollars. Generally, younger applicants will receive lower premium quotes because they are viewed as lower risk. The premiums increase as you age, highlighting the benefit of securing Life Insurance at a younger age.

          A term Life Insurance policy for a million dollars provides coverage for a specific period, such as 10, 20, or 30 years, and pays out only if the insured person dies within that term. A permanent Life Insurance policy, however, offers lifelong coverage and includes a cash value component that grows over time, but it comes with significantly higher premium rates.

          Qualifying for a Million Dollar Life Insurance Policy depends on several factors, including your age, health, lifestyle, and financial situation. While it might be more challenging for those with health issues or older applicants, many healthy individuals find they can qualify for such policies, especially with thorough preparation and selecting the right insurer.

          The duration of a Million Dollar Life Insurance Policy depends on the type of policy you choose. Term policies last for a predetermined period, while permanent policies, such as Whole Life Insurance or Universal Life Insurance provide coverage for your entire life as long as premiums are paid.

          Yes, you can have multiple Life Insurance policies from different insurers or a combination of term and permanent policies that together provide a million dollars in coverage. This strategy can offer flexibility and ensure that your coverage meets your evolving financial needs.

          While there are no hidden costs, it’s important to understand all the aspects of your policy, including premium rates, potential policy fees, and costs associated with increasing coverage or borrowing against a policy’s cash value. Always read the fine print and ask your insurance agent to clarify any points you do not understand.

          To potentially lower the cost of your premium, consider buying Life Insurance at a younger age, maintaining a healthy lifestyle, avoiding tobacco, and choosing a term policy over a permanent one. Comparing quotes from multiple insurers can also help you find the most competitive rates for a Million Dollar Policy Insurance quote.

          Your health and family medical history significantly influence Life Insurance costs. Insurers evaluate your current health conditions and family history of hereditary diseases to assess risk, potentially increasing premiums for those with higher health risks. A clean bill of health and a lack of genetic severe conditions in your family can lead to lower premiums, reflecting a lower risk for the insurance company.

          Whether a Million Dollar Life Insurance Policy is worth it depends on your financial situation and coverage needs. For those with significant debts, dependents, and a high earning potential, such a policy ensures financial security for your family without burdening them in your absence. If the premiums are affordable within your budget, investing in a million-dollar policy can offer valuable mental peace and financial protection for your loved ones.

          The above information is only meant to be informative. It comes from Canadian LIC’s own opinions, which can change at any time. This material is not meant to be financial or legal advice, and it should not be interpreted as such. If someone decides to act on the information on this page, Canadian LIC is not responsible for what happens. Every attempt is made to provide accurate and up-to-date information on Canadian LIC. Some of the terms, conditions, limitations, exclusions, termination, and other parts of the policies mentioned above may not be included, which may be important to the policy choice. For full details, please refer to the actual policy documents. If there is any disagreement, the language in the actual policy documents will be used. All rights reserved.

          Please let us know if there is anything that should be updated, removed, or corrected from this article. Send an email to Contact@canadianlic.com or Info@canadianlic.com

          Can I Get a Million Dollar Life Insurance Policy Without a Medical Exam?

          The idea of getting a Life Insurance policy, especially one as big as a million dollars, usually means going through multiple rounds of medical exams. It’s understandable; insurers have traditionally used these exams to assess the risk levels of applicants. But as the Canadian Life Insurance market changes, it’s now possible to get a million-dollar insurance without having to go through a medical exam. This blog aims to explore this possibility, focusing on making the information accessible to everyone.

          Can I Get a Million Dollar Life Insurance Policy Without a Medical Exam?

          By Canadian LIC, March 1, 2024, 12 Minutes

          Can I Get a Million Dollar Life Insurance Policy Without a Medical Exam?

          The idea of getting a Life Insurance policy, especially one as big as a million dollars, usually means going through multiple rounds of medical exams. It’s understandable; insurers have traditionally used these exams to assess the risk levels of applicants. But as the Canadian Life Insurance market changes, it’s now possible to get a million-dollar insurance without having to go through a medical exam. This blog aims to explore this possibility, focusing on making the information accessible to everyone.

          Understanding the Basics

          Let’s define what we mean by a “Million Dollar Insurance Policy” first. In simple terms, this is a Life Insurance policy that guarantees your beneficiaries will get a million dollars in the event of your death. It’s a significant amount intended to meet major expenses such as mortgage repayments, education costs for children, and providing financial security for your loved ones.

          Find Out: How a Million Dollar Life Insurance Policy Paid Out?

          Find Out: Is it possible to have a Million Dollar Life Insurance Policy?

          Is a Medical Exam Always Required?

          Traditionally, obtaining any Life Insurance policy, including a policy for a million dollars, would require a comprehensive medical exam. This would help the insurance company determine your health status and, by extension, your risk level. However, advancements in technology and changes in the insurance industry have paved the way for policies that don’t require a medical exam.

          Options in Canada

          In Canada, the option to secure a Million Dollar Life Insurance Policy without a medical exam is indeed available. This has become possible thanks to simplified issue Life Insurance policies and guaranteed issue Life Insurance policies. Let’s look at what these terms mean: Simplified Issue Life Insurance: This type of policy typically doesn’t require a medical exam. Instead, you’ll answer a series of health-related questions. The fewer the questions and the more “no” answers you can give, the better your chances of being approved for coverage. Guaranteed Issue Life Insurance: As the name suggests, these policies guarantee coverage without any medical exams or health questions. While this sounds ideal, it’s worth noting that these policies often come with higher premiums and lower coverage limits. However, securing a Million Dollar Policy through this route may be challenging and involve piecing together multiple policies.

          How Does It Work?

          Securing a Life Insurance policy worth a million dollars without undergoing a medical exam might sound too good to be true. Yet, with advancements in technology and a customer-centric approach, insurers in Canada are making this a reality for many. Here’s how this innovative process works:

          Sophisticated Algorithms: Insurance companies employ advanced algorithms that analyze a wide range of data points to accurately evaluate the risk of insuring an individual. This method allows for a swift evaluation process, bypassing traditional medical exams.

          Comprehensive Questionnaires: You’ll be asked to complete a detailed questionnaire instead of a physical exam. Your answers provide insights into your health and lifestyle, crucial factors insurers use to determine your eligibility for a Million Dollar Insurance Policy.

          Data Analysis: Insurers analyze your health information, sometimes including data from medical databases, to make an informed decision. This process ensures that the assessment is both thorough and fair.

          Instant Coverage Decisions: Thanks to this streamlined approach, decisions on policy approval can be made much faster than traditional methods, offering you immediate peace of mind.

          Real-Life Examples: Securing a Million Dollar Policy Without Stepping into a Doctor’s Office

          To bring this concept closer to home, let’s explore some scenarios where individuals successfully obtained a million dollars Life Insurance coverage without a medical exam:

          Case Study: Sarah, the Entrepreneur: Sarah, a 35-year-old entrepreneur, has a busy life balancing her startup and family. Knowing the importance of securing her family’s financial future but lacking the time for medical exams, she opts for a simplified issue Life Insurance policy. Her healthy lifestyle and positive answers on the questionnaire led to her quick approval for a Million Dollar Insurance Policy, ensuring her family’s financial security and giving her one less thing to worry about.

          Case Study: Michael, the Freelancer: Michael, a 45-year-old freelance graphic designer, has always prioritized his health. However, a few minor health issues in the past made him wary of the traditional insurance process. Discovering he could apply for a Million Dollar Life Insurance Policy without a medical exam was a game-changer. By accurately reporting his health status and lifestyle in the questionnaire, Michael secures the coverage he needs, protecting his family’s future without the stress of a medical exam.

          Case Study: Linda and Alex, the Adventurous Couple: Linda and Alex, a couple in their early 50s, love adventure and travel. Concerned about their grown children’s future and well-being, they seek a joint Life Insurance policy. Their active lifestyle and good health make them ideal candidates for a no-medical exam policy. Within weeks, they’re approved for a Million Dollar Policy, ensuring their adventures don’t come with financial risks for their family.

          Get The Best Insurance Quote From Canadian L.I.C

          Call 1 844-542-4678 to speak to our advisors.

          Canadianlic best insurance quote

          Making It Work for You

          These examples illustrate that securing a significant Life Insurance policy without the traditional hurdles is possible whether you’re a busy professional, a freelancer with a complex health history, or part of an adventurous duo. Here are steps to make this option work for you:

          Research: Start by researching insurers in Canada that offer million-dollar policies without a medical exam. Read customer reviews and ratings to make sure you’re choosing a reputable company.

          Prepare Your Information: Be ready to provide detailed information about your health, lifestyle, and medical history. Accuracy is key to ensuring your application is processed smoothly.

          Consult a Professional: Consider speaking with a financial advisor or insurance broker. They can give you personal advice and help you easily go through the application process.

          Review and Apply: Once you’ve selected an insurer, carefully review their policy terms and complete the application process. Remember, honesty in your questionnaire is crucial for a valid policy.

          Why Consider a Million Dollar Policy Without a Medical Exam?

          When it comes to securing a future for your loved ones, the thought of obtaining a Million Dollar Insurance Policy might seem like a daunting task, especially if you’re concerned about the medical exam process. However, the evolution of the insurance industry has introduced more accessible ways to achieve this level of coverage without the traditional hurdles. Let’s go deep into the reasons why a no-medical exam, Million Dollar Life Insurance Policy might be the right choice for you.

          Convenience: Streamlining the Application Process

          The appeal of bypassing the medical exam cannot be overstated. For many, the traditional route of securing a Million Dollar Life Insurance Policy involves scheduling an appointment, undergoing a physical examination, and waiting for lab results. This can be time-consuming and, for some, a logistical nightmare, especially for those with busy schedules or who live in remote areas.

          Opting for a no-medical exam policy means you can apply online or over the phone, answering a series of health-related questions without needing to see a doctor physically. This streamlined process can drastically reduce the time from application to approval, making it an attractive choice for all those who are looking for convenience without compromising on the level of coverage.

          Imagine, for instance, a busy parent like Sarah, who juggles work and family commitments. Finding the time for a medical exam could mean postponing her application indefinitely. A no-medical exam Million Dollar Insurance Policy becomes not just a convenience but a necessity, enabling her to secure her family’s financial future swiftly and efficiently.

          Health Concerns: Opening Doors for More Applicants

          Traditional Life Insurance policies often put individuals with pre-existing conditions in a tough spot. The fear of being denied coverage or facing very high premiums can discourage many from applying. However, all this is changing with the availability of million-dollar insurance policies without a medical exam. This inclusivity means that more people can obtain substantial coverage regardless of their health status.

          Take Mark, for example, who was diagnosed with a chronic condition a few years ago. Under traditional underwriting processes, Mark might face higher premiums or even denial. However, with a no medical exam policy, he can secure a million-dollar coverage without his condition being a barrier. This opens up a world of possibilities for individuals like Mark, ensuring they can provide for their loved ones without being penalized for their health status.

          Immediate Coverage: Faster Protection for Your Loved Ones

          The need for immediate protection cannot be understated, especially in uncertain times. Traditional Life Insurance applications can take weeks or even months to process. In contrast, no-medical exam policies offer a swift pathway to securing coverage, often within days of applying. This rapid turnaround is essential for those who find themselves suddenly aware of the fragility of life, perhaps due to a recent health scare or the loss of a loved one.

          Consider the scenario of Emily, who recently experienced the sudden loss of a close friend. This event prompted her to think about her own family’s financial security. The prospect of waiting months for coverage is unappealing and anxiety-inducing. The availability of a Million Dollar Life Insurance Policy without the wait means Emily can secure her family’s financial future almost immediately, providing her with mental peace during a troubled time.

          Things to Keep in Mind

          • Cost: Premiums for policies that don’t require a medical exam can be higher, reflecting the increased risk the insurer takes on by not checking your health in detail.
          • Coverage Limits: While getting a million dollars in coverage is possible, the options may be more limited than with traditional policies.
          • Terms and Conditions: Always read the fine print to understand what you’re buying and to ensure it meets your needs.

          The Bottom Line

          Hence, it is now possible to buy a Million Dollar Life Insurance Policy without having to undergo a medical examination. For many, it’s a good alternative because it provides convenience and comfort. But it’s important to balance the advantages and disadvantages, think about your financial objectives, and speak with an insurance broker or financial advisor. They can assist you in sorting through the choices and finding a coverage that meets both your needs and your budget.

          Protecting your family’s financial future right now is both a logical and loving thing to do. Million-dollar Life Insurance policies can offer great protection, and the ability to purchase one without a medical exam opens doors for many who might have thought it was out of reach. If you want to feel at ease, start by doing some research and getting quotes.

          Get The Best Insurance Quote From Canadian L.I.C

          Call 1 844-542-4678 to speak to our advisors.

          FAQs

          A Million Dollar Insurance Policy is a type of Life Insurance coverage where the insurer agrees to pay your beneficiaries a $1,000,000 death benefit upon your passing. This substantial sum can provide significant financial security for your loved ones, covering everything from daily living expenses to large debts like mortgages. It’s like having a financial safety net, ensuring your family’s future is protected, even in your absence.

          Yes, you certainly can! Whether you’re a high-earning professional, a business owner, or someone with significant financial responsibilities, a Million Dollar Insurance Policy is within reach. Providers often look at your income, health, and lifestyle to determine eligibility.

          Individuals with substantial financial obligations or those looking to leave a significant financial legacy could benefit from a Million Dollar Life Insurance Policy. If you have a large mortgage, plan to fund your children’s education, or wish to ensure your family maintains their living standard, this coverage level might be for you.

          The cost varies largely based on factors such as age, health, lifestyle, and the type of policy (Term Life Insurance, Whole Life Insurance, or Universal Life Insurance). Younger, healthier individuals will generally pay lower premiums. For example, a healthy 30-year-old might pay significantly less per month than someone applying at 50.

          Depending on your age, health, and policy type, monthly premiums for a million-dollar coverage can range from a few hundred to over a thousand dollars. A term policy is typically less expensive than permanent coverage. Using a hypothetical scenario, Jordan, a 35-year-old non-smoker, might pay around $50 to $100 per month for a term policy.

          Upon the policyholder’s death, a Million Dollar Life Insurance Policy pays out a death benefit of $1,000,000 to the designated beneficiaries. This payout is usually tax-free, providing significant financial support to cover estate settlements, debts, and living expenses for your loved ones.

          Absolutely! Whether you’re a busy professional like Sarah, who can’t find the time for medical appointments, or someone with pre-existing conditions like Mark, no-medical exam policies are designed to be inclusive. These policies cater to a wide audience, ensuring that more Canadians have access to substantial Life Insurance coverage. However, eligibility can vary based on the insurance provider, so discussing your specific situation with an insurance advisor is essential.

          A Million Dollar Policy makes sense when your financial obligations or goals exceed lesser coverage amounts. If ensuring your family’s lifestyle, covering your debts, and providing for future expenses like education and retirement are your priorities, this level of coverage is worth considering. For example, if you’re like Priya, who owns a business and has two young children, a Million Dollar Policy could provide the mental peace that your financial responsibilities are covered.

          There are primarily two types: simplified issue and guaranteed issue Life Insurance. Simplified issue policies require answers to health questions but no medical exam. Guaranteed-issue policies require no health questions or exams but might offer lower coverage amounts and higher premiums. These options provide flexibility for those concerned about medical exams affecting their eligibility.

          Applying for a no-medical exam Million Dollar Life Insurance Policy is straightforward. You’ll typically fill out an application and answer some health-related questions online or over the phone. Your medical records may also be requested by your insurer. The process is quick, often resulting in approval within a few days to a week.

          The approval time can be surprisingly swift. In cases like Emily’s, who sought immediate coverage following a personal wake-up call, approval can come within days. One of the best things about a no-medical exam policy is that it gets you approved quickly because you don’t have to wait like you do with regular medical underwriting.

          Generally speaking, yes. Since insurance companies take on a higher risk by offering policies without a medical exam, the premiums can be higher to offset this risk. However, the convenience and accessibility of securing a policy without an exam can make the extra cost worthwhile for many. It’s all about balancing the need for immediate, inclusive coverage against the cost.

          Yes, it’s possible. Policies like guaranteed issue Life Insurance don’t require any health questions or medical exams, making them accessible even to those with serious health conditions. While these policies might come with certain limitations, such as higher premiums or graded death benefits, they ensure that coverage is attainable. It’s about providing peace to people from all health backgrounds.

          Evaluating whether a no-medical exam policy is the right fit depends on several factors, including your health, financial goals, and the urgency of coverage. A no-medical exam policy is ideal if you value convenience and speed and are concerned about how your health might affect your eligibility for traditional coverage. Speaking with a knowledgeable insurance advisor can help you understand your options and make the best decision.

          Indeed, you can. If you find that a single no-medical exam policy doesn’t offer the full million-dollar coverage you’re seeking, you might consider layering different policies. This strategy can provide the complete protection you’re looking for. Insurance advisors often recommend this approach to tailor coverage to your specific financial goals and needs.

          Research is key. Start by consulting with insurance brokers or financial advisors who specialize in Life Insurance. They can provide insights into which companies offer the best rates, coverage, and customer service for no-medical exam policies. Additionally, looking at reviews and ratings from financial institutions can give you a sense of the company’s reliability and the quality of its products.

          If you’re unable to qualify for a no medical exam policy, consider applying for a traditional policy with a medical exam. These policies can be more forgiving of certain health issues and offer more competitive rates. Working with an insurance broker can also help find Life Insurance companies more suited to your specific health profile.

          The above information is only meant to be informative. It comes from Canadian LIC’s own opinions, which can change at any time. This material is not meant to be financial or legal advice, and it should not be interpreted as such. If someone decides to act on the information on this page, Canadian LIC is not responsible for what happens. Every attempt is made to provide accurate and up-to-date information on Canadian LIC. Some of the terms, conditions, limitations, exclusions, termination, and other parts of the policies mentioned above may not be included, which may be important to the policy choice. For full details, please refer to the actual policy documents. If there is any disagreement, the language in the actual policy documents will be used. All rights reserved.

          Please let us know if there is anything that should be updated, removed, or corrected from this article. Send an email to Contact@canadianlic.com or Info@canadianlic.com

          How is a Million Dollar Life Insurance Policy Paid Out?

          Life Insurance is given a lot of importance when it comes to financial protection, especially when considering policies like Million Dollar Life Insurance. It’s essential to comprehend how such policies pay out to ensure clarity and security for beneficiaries.

          How is a Million Dollar Life Insurance Policy Paid Out?

          By Harpreet Puri, December 20, 2023, 7 Minutes

          How is a Million Dollar Life Insurance Policy Paid Out

          Life Insurance is given a lot of importance when it comes to financial protection, especially when considering policies like a Million Dollar Life Insurance Policy. A Million Dollar Insurance Policy is not just about leaving behind a large sum—it’s about securing your family’s future with clarity and confidence. Many Canadians choose this level of coverage to ensure their loved ones are not financially burdened after their passing. Understanding how a Million Dollar Life Insurance Policy is paid out helps beneficiaries prepare better and avoid delays during emotionally difficult times. Whether it’s for replacing income, paying off large debts, or supporting long-term goals, this kind of insurance policy plays a crucial role in comprehensive financial planning.

          How Does It Work?

          A Million Dollar Life Insurance Policy stands as a pivotal financial protection designed to provide substantial coverage to beneficiaries upon the insured person’s passing. This policy is structured to offer a lump-sum payment, often referred to as the death benefit, amounting to one million dollars. This significant payout aims to serve as a very important financial safety guard for the insured person’s loved ones in the event of an unexpected demise.

          Coverage Aim and Implications:

          The gravity of a Million Dollar Insurance Policy is that it should cover all financial liabilities of the family members and provide for the needs of the dependents. This large amount of coverage has a definite purpose; it’s designed to give a financial buffer to anyone who is financially dependent on the insured after the insured person dies.

          The figure behind this coverage, generally a million dollars, is based on a list of financial needs and commitments that are going to surface following the death of the insured.

          Beneficiary Support and Financial Security:

          When the insured person passes away, the recipients they’ve chosen—normally family or dependents—are eligible to receive this significant death benefit. This money will be used for a variety of purposes, including paying for short-term expenses such as funeral costs, unpaid debts, and mortgage payments, to providing long-term financial support.

          It may provide continuous support to the beneficiaries, enabling them to continue their lifestyle or achieve future objectives without any stress about money.

          Role in Comprehensive Financial Planning:

          A Million Dollar Insurance Coverage is typically an important component of an overall financial plan for a person. It’s the foundation for safeguarding the financial future of those who matter to you, and much more: It is a tool for helping to protect their financial future. This sound coverage brings peace of mind in troubled times, as it helps recipients cope with the repercussions of a death without the burden of costly expenses.

          Find out more about Million Dollar Life Insurance Policy

          How Timing and Financial Planning Influence the Impact of a Million Dollar Insurance Policy

          A lesser-known yet crucial factor in optimizing the benefits of a Million Dollar Insurance Policy lies in the timing of its purchase and the coordination with broader financial planning strategies. Many individuals view life insurance as a standalone product, but those with high-net-worth goals often integrate it into a comprehensive estate and legacy planning framework. This strategic approach is not widely discussed, yet it can significantly influence how impactful the policy becomes for beneficiaries.

          Purchasing a Million Dollar Insurance Policy at a younger age not only results in lower premiums but can also open opportunities to align the policy’s payout timeline with major life milestones of the beneficiaries, such as university expenses, home purchases, or even retirement support. Coordinating this policy with trusts or structured inheritances can allow families to manage tax exposure, fund intergenerational wealth transfers, or protect business continuity.

          This proactive planning ensures the death benefit doesn’t merely serve as reactive support after loss, but as a tool for long-term empowerment. Unlike general coverage, this kind of foresight turns the policy into a generational asset.

          When combined with trusted financial advice and legal structures, a million-dollar benefit does more than provide—it transforms futures.

          The Payout Process of Million Dollar Life Insurance Coverage

          The Payout Process of Million Dollar Life Insurance Coverage

          Let’s understand it with the following points:

          Initiating the Claim:

          In case of the death of the insured, the nominees have to get in touch with the insurance company to aid the claim process without delay. This crucial step entails contacting the insurer, giving them the news of the passing of the insured person, and to get the ball rolling on the formal claim process for the Million Dollar Insurance Coverage.

          Document Submission:

          When an heir calls on the insurer, they’re walked through the paperwork that will need to be filed. This generally requires that certain forms are filed with necessary paperwork, including the death certificate, proving the life insured has passed on. Furthermore, ready access to policy details makes it easy to file claims on the Million Dollar Life Insurance Policy.

          Claims Evaluation:

          The insurance company reviews the submitted claim once the essential documents are received. This evaluation phase serves as a critical checkpoint, where the insurer assesses if the claim adheres to the policy’s conditions. Simultaneously, they confirm that premiums for the Million Dollar Insurance Coverage are up to date.

          Validation and Payout:

          If the insurer successfully validates the claim, it will not hesitate to pay the handsome death benefit in accordance with the terms of the policy. This fateful scene is the culmination of the claims process, as the beneficiaries collect their planned-for million-dollar payday.

          Tax-Free Nature

          Canadian Tax Regulations:

          Benefits of a Million Dollar Insurance Policy for Both Canadian and U.S Residents. In Canada, the tax status of the proceeds of Life Insurance, including a fat check of Life Insurance proceeds from a Million Dollar Insurance Policy, is very advantageous to the beneficiaries. The tax-free nature of the benefit can be particularly appealing since many other types of income, and benefits themselves, are subject to different taxes, and even if the death benefit of a Life Insurance Policy provides a million dollars, the death proceeds from the policy are almost always tax-free for beneficiaries.

          Financial Relief for Beneficiaries:

          This tax relief is especially significant at the emotional time of a person’s death. Because the Million Dollar Insurance Coverage is tax-free, the full benefit amount goes to survivors, offering significant financial assistance while avoiding taxes on the benefit received.

          Utilizing the Full Benefit:

          The tax-free nature of the Million Dollar Insurance Policy payout empowers beneficiaries to utilize the entire lump sum as intended. This allows them to address various financial needs comprehensively, ranging from immediate expenses such as funeral costs or outstanding debts to securing long-term financial stability for themselves and their families.

          Impact on Financial Planning:

          This tax-free status is extremely significant in financial planning. Recipients need only to allocate the received million-dollar benefit and can do so with the confidence that the money will not erode from taxes, giving them greater financial autonomy to make sound financial choices as needed in the short term and long term.

          The tax advantage of Life Insurance in Canada, especially a large Million Dollar Insurance Policy, is an important advantage for a beneficiary. This exemption provides financial relief during a difficult time, since it allows beneficiaries to receive the entire death benefit without being subject to taxes.

          Utilizing the Payout

          Beneficiaries have the freedom to use the million-dollar benefit they receive according to their needs. Common uses include:

          Addressing Immediate Needs:

          With the nice big million-dollar benefit from the insurance, beneficiaries have options to invest those proceeds based on what their financial needs are at that time. Generally speaking, they cover the cost of any immediate needs that come up when the policyholder dies:

          • Funeral Expenses: The payout can be used to pay for the funeral, and ensure the funeral is not a financial burden on the family while their emotions are tested.
          • Debts: If preferred, the beneficiaries are able to use some of the annuity payment to cover financial debts and have a clean break.

          Mortgage Repayments: The received benefit can also be applied to paying down a mortgage, keeping up with mortgage repayments, and protecting the family home.

          Ensuring Long-Term Financial Stability:

          But beyond these immediate costs, the Million Dollar Insurance Coverage may be a chance of a lifetime for your loved ones to ensure their financial security for years to come:

          • Investing for security of tomorrow: Some beneficiaries may prefer to save a part of the benefit received to safeguard the family’s future. This might include setting up investment portfolios or savings accounts to add to your regular income.
          • Education and Missionary: Many choose to apply a budget towards children’s or grandchildren’s education. It gives recipients the ability to view the future by investing in education with less tension of a monetary burden.

          Income Replacement: There are many scenarios in which income loss affects the family as opposed to the insured, but the cash provided will allow the loss of the benefit to be replaced, meaning the family’s stability remains intact.

          Strategic Financial Decision-Making:

          Since the Million Dollar Insurance Policy payment can be used for a number of purposes, the knowledge of this dynamic variety of functions alerts the beneficiaries and guides them to make the right decisions. The percentage of the benefit set aside between the immediate and the long-term needs should allow the beneficiary to maximize the benefit for their particular needs today and tomorrow.

          Payment of a Million Dollar Insurance Policy is flexible to enable beneficiaries to maneuver the financial pressures. Whether to cover existing debts or make a smart investment for the future, the value of the benefit amount cannot be overlooked as a crucial aid to help achieve long-term financial security and secure financial stability and future comfort of the beneficiaries.

          Considerations

          These considerations need to be kept in mind:

          Understanding Policy Details:

          Beneficiaries of a Million Dollar Insurance Policy must familiarize themselves with the policy’s intricate details to ensure a smooth claims process and proper utilization of the benefits:

          • Terms of Coverage: You need to be very clear about the terms of coverage. Know: Beneficiaries should understand which critical illnesses or conditions are provided for by the policy, and the details of the death benefit.
          • Nominee Declarations: A nominee is the assigned beneficiary, and this list can help guarantee that the possible Million Dollar Life Insurance Policy reaches the right people. Correct beneficiary designations are essential for the proceeds to go to the appropriate people.
          • Contact Information: Save the insurance company’s contact information, since you may need to use it in case a claim occurs, and that can help you get your claim processed and paid out faster.

          Regular Review of Beneficiary Designations:

          Regular review and, if necessary, revision of your beneficiaries is important to ensure your designations reflect changes in life events:

          • Life changes: Significant life events, including marriages, divorces, births, and deaths within the family, may require a change to beneficiary designations. Such timely updates in the policy ensure no confusion at the time of the distribution of benefits.

          Precision and Purpose: One should review beneficiary designations to ensure that both accuracy and agreement with his or her wishes are reflected. Updates keep the accuracy and relevance of the game in tune with the evolving family dynamic.

          Importance of Clear Communication:

          Open communication among family members is extremely crucial. The insured person should communicate the policy’s existence, details, and intended beneficiaries to avoid confusion or disputes among family members during a challenging time.

          Ensuring Smooth Execution:

          It is a proactive process to know the policy details and review the beneficiary designations on a regular basis. The Million Dollar Insurance Coverage is guaranteed to be directed where it’s needed most, without interference, allowing the financial protection options to remain intact.

          Having knowledge about the policy’s fine print and the importance of keeping your beneficiary updated still can count as a necessary part to manage a Million Dollar Insurance Policy. Being informed and keeping information up-to-date allows beneficiaries to easily navigate through the process, to even receive a significant benefit, giving much-needed financial assistance at a difficult time.

          Earning a Million Dollar Life Insurance Policy plan represents a powerful monetary version, and it offers great protection from the illness or death of the insured person. Having a good grasp of the payout and tax-free nature of the benefits associated with these great products will definitely give some peace of mind and allow those who are to receive them to make wiser decisions on how much they deserve, even before they buy a Million Dollar Life Insurance Policy.

          For additional information on Million Dollar Insurance Coverage or an explanation about how these polices work, insurance professionals can provide customized advice depending on a person’s specific situation.

          Get The Best Insurance Quote From Canadian L.I.C

          Call 1 844-542-4678 to speak to our advisors.

          Canadianlic best insurance quote

          Faq's

          A Million Dollar Life Insurance Policy typically gives out a lump-sum payment to beneficiaries upon the death of the insured person. The coverage terms usually include specified critical illnesses or conditions outlined in the policy.

          Familiarize yourself with the Million Dollar Life Insurance Policy’s beneficiary designations. Review and update these designations on a regular basis to reflect any life changes, ensuring the benefit reaches the right recipients.

          Contact the insurance company promptly to update beneficiary details. Provide accurate and updated information to ensure the intended recipients receive the Million Dollar Life Insurance Policy.

          Necessary documents may include the death certificate, policy details, and beneficiary information. Ensure these documents are readily available for a smooth claims process.

          Yes, beneficiaries have the flexibility to use the received benefit according to their needs. It can cover immediate expenses like funeral costs and outstanding debts or be invested for long-term financial security.

          It’s advisable to review the Million Dollar Life Insurance Coverage details and beneficiary designations in a periodic manner or after significant life events to ensure accuracy and alignment with current intentions.

          In Canada, Life Insurance proceeds, including a million-dollar benefit, are generally tax-free for beneficiaries. This tax exemption offers significant financial relief during a difficult time.

          Contact the insurance company directly for any inquiries regarding the policy, claims process, or any concerns related to managing the Million Dollar Life Insurance Coverage.

          Yes, it’s beneficial to communicate the Million Dollar Life Insurance Policy’s existence, details, and intended beneficiaries to family members to avoid confusion or disputes regarding the benefit distribution.

          Understanding the Million Dollar Life Insurance Policy details, maintaining accurate beneficiary designations, and keeping necessary documents readily available facilitate a seamless claims process, ensuring the benefit reaches the intended recipients efficiently.

          Beneficiaries need to contact the insurance company to initiate the claims process. This typically involves submitting necessary documents such as the death certificate and policy details.

          Communication is key. Inform beneficiaries about the policy’s specifics, coverage terms, and beneficiary designations, and provide contact information for the insurance company.

          Yes, it’s possible to designate multiple beneficiaries. Ensure that the shares or percentages allocated to each beneficiary are clearly outlined in the policy.

          Seeking guidance from financial advisors or legal professionals can offer valuable insights, especially when considering updates to beneficiary designations or navigating the claims process.

          A lapsed Million Dollar Life Insurance Policy or non-payment of premiums may impact the benefits. It’s crucial to ensure timely premium payments to maintain coverage and avoid potential lapses.

          Generally, beneficiaries have the freedom to use the received benefit according to their needs. However, understanding any specific limitations outlined in the Million Dollar Life Insurance Policy is advisable.

          Yes, designating a trust as a beneficiary is possible. Consult legal professionals to understand the implications and ensure proper documentation for trust designations.

          Exclusions specified in the Million Dollar Life Insurance Policy might affect the claims process. Understanding policy exclusions and their implications is crucial for a realistic expectation of the coverage.

          Some policies may offer conversion options. Contact the insurance company to inquire about potential conversion opportunities, depending on the policy terms.

          In case of disputes, seek resolution through communication with the insurance company or legal guidance if necessary to ensure fair and accurate benefit distribution.

          The above information is only meant to be informative. It comes from Canadian LIC’s own opinions, which can change at any time. This material is not meant to be financial or legal advice, and it should not be interpreted as such. If someone decides to act on the information on this page, Canadian LIC is not responsible for what happens. Every attempt is made to provide accurate and up-to-date information on Canadian LIC. Some of the terms, conditions, limitations, exclusions, termination, and other parts of the policies mentioned above may not be included, which may be important to the policy choice. For full details, please refer to the actual policy documents. If there is any disagreement, the language in the actual policy documents will be used. All rights reserved.

          Please let us know if there is anything that should be updated, removed, or corrected from this article. Send an email to Contact@canadianlic.com or Info@canadianlic.com

          Is it Possible to have a Million Dollar Life Insurance Policy?

          In the realm of life insurance, a million-dollar policy stands out as a significant financial safeguard. This level of policy is not just a number; it’s a comprehensive plan designed to offer extensive protection and support to the policyholder’s beneficiaries in the event of their untimely demise. When we talk about a Million-Dollar Life

          Is it Possible to have a Million Dollar Life Insurance Policy?

          By Harpreet Puri, November 15, 2023, 8 Minutes

          Is it Possible to have a Million Dollar Life Insurance Policy

          In the realm of life insurance, a million-dollar policy stands out as a significant financial safeguard. This level of policy is not just a number; it’s a comprehensive plan designed to offer extensive protection and support to the policyholder’s beneficiaries in the event of their untimely demise. When we talk about a Million-Dollar Life Insurance Policy in Canada, we’re referring to the policy’s death benefit – which is basically the amount paid out to beneficiaries upon the policyholder’s death.

          A Million-Dollar Life Insurance Policy is often associated with high-net-worth individuals, but it’s not exclusively for the wealthy. In reality, it can be a practical choice for many middle-class families as well, especially those with substantial financial obligations or long-term financial goals.

          This policy is suitable for people who have sizable debts, such as mortgages or business loans and want to ensure these are not a burden to their family in the case of their passing. It’s also ideal for those aiming to provide substantial income replacement, ensuring that their family can maintain their standard of living for several years following their death.

          Furthermore, for those involved in estate planning, a million-dollar policy can serve as a strategic tool to manage potential estate taxes or leave a substantial legacy. It’s about ensuring that your financial responsibilities and aspirations for your family are taken care of, even in your absence. Obtaining such a policy requires careful consideration of your current financial status, future goals, and the needs of your dependents.

          What is a Million Dollar Life Insurance Policy?

          Aspect Description
          Definition A Million Dollar Life Insurance Policy in Canada is a type of life insurance that offers a death benefit of one million dollars to the beneficiaries upon the policyholder’s death.
          Purpose This policy is designed to provide significant financial security and support to the beneficiaries, helping cover large financial obligations, replace income, or achieve specific future goals.
          Suitability Ideal for individuals with high income, substantial debts, long-term financial goals for dependents, business owners, or those involved in estate planning.
          Types of Policies Can be either Term Life Insurance (coverage for a specific period) or permanent life insurance (Whole Life or Universal Life, offering lifelong coverage and possibly an investment component).
          Cost Factors Premiums depend on the policyholder’s age, health, lifestyle, type of insurance, and additional features or riders. Younger and healthier individuals typically pay lower premiums.
          Eligibility Criteria Insurers consider income levels, health status, age, lifestyle, and the overall financial justification for the coverage amount.
          Underwriting Process Often involves a comprehensive evaluation including a medical exam, lifestyle assessment, and financial analysis.
          Benefits Provides substantial financial coverage for beneficiaries, can cover major debts, fund future goals, and aid in estate planning.
          Tax Implications Generally, the death benefit from a life insurance policy in Canada, including a million-dollar policy, is not taxable to the beneficiaries.
          Considerations Requires careful assessment of financial needs and goals, and often consultation with financial advisors to ensure alignment with personal financial strategies.

          Who Needs a Million-Dollar Life Insurance Policy?

          The need for a Million-Dollar Life Insurance Policy in Canada is not universal but is highly dependent on individual circumstances. It becomes a consideration for those whose financial obligations and goals exceed the average, necessitating larger coverage to protect their loved ones adequately.

          Individuals with Significant Debts: If you have high-value liabilities like a large mortgage, business loans, or other substantial debts, a million-dollar policy ensures these do not become a burden for your family after you’re gone. This policy size helps in fully covering such debts, providing a clear financial path for your beneficiaries.

          Primary Breadwinners: For families where one person significantly contributes to the household income, a policy of this magnitude can replace several years’ worth of income. This ensures that in the event of the breadwinner’s untimely death, the family’s financial needs – from day-to-day expenses to long-term goals like children’s education – are securely met.

          Funding Future Goals: A million-dollar policy can be an effective way to fund future aspirations, whether it’s your children’s higher education, ensuring a comfortable retirement for your spouse, or other long-term financial goals. It acts as a financial safety net, ensuring that your dreams for your family do not perish with you.

          Estate Planning and Legacy Creation: For those engaged in estate planning, this level of coverage can help in managing estate taxes, thus protecting the value of the estate for the beneficiaries. It also allows individuals to leave a substantial legacy, be it in the form of charitable donations or a financial inheritance for their heirs.

          Eligibility for a Million-Dollar Policy

          Securing a Million-Dollar Life Insurance Policy in Canada is subject to meeting certain eligibility criteria, as insurers need to assess the risk and justification for such a high coverage amount.

          Income Verification: Insurers typically require proof that your income supports the premiums for a policy of this size. They use this to gauge whether the policy is financially justifiable and sustainable for you.

          Health and Medical History: A thorough health examination is usually mandatory. Insurers assess your current health, medical history, and any potential risks to determine your eligibility. A clean bill of health can lead to more favourable terms, while pre-existing conditions may increase the premiums or impact eligibility.

          Age Considerations: Age is a critical factor. Younger-aged individuals are more likely to qualify for a million-dollar policy at a reasonable cost since the risk to the insurer is lower compared to older applicants.

          Financial Justification: Besides income, insurers also consider your overall financial situation. They evaluate if the coverage amount aligns with your current liabilities, dependents’ needs, and future financial goals. The aim is to ensure that the policy is not excessively beyond what is needed or what can be reasonably afforded.

          Cost of a Million-Dollar Life Insurance Policy

          The premiums for a Million-Dollar Life Insurance Policy in Canada can vary widely, influenced by several factors. It’s important to note that such a policy is a significant financial commitment, and understanding these factors can help in assessing its affordability.

          Policy Type: Term Life Insurance policies tend to have lower premiums compared to whole-life or universal life policies. The choice between term and permanent insurance will significantly impact the cost.

          Personal Factors: Age, health, and lifestyle choices are primary determinants of premium costs. Younger, healthier individuals usually benefit from lower rates, while factors like smoking or a high-risk lifestyle can lead to higher premiums.

          Policy Features: The inclusion of riders or additional benefits can also affect the cost. For instance, a policy with a critical illness rider will be more expensive than a standard policy.

          Underwriting Process: The underwriting process, where insurers evaluate your risk, plays a crucial role in determining the premiums. A thorough evaluation during this process can lead to more accurately priced premiums based on your specific risk profile.

          How to Buy a Million-Dollar Life Insurance Policy?

          Purchasing a million-dollar life insurance coverage in Canada is a crucial decision that needs careful planning and consideration. Here’s a step-by-step guide to help you navigate the process:

          Assess Your Financial Needs

          Before purchasing a policy, it’s crucial to determine if a million-dollar policy is appropriate for your situation. Consider your financial obligations, future goals, and your dependents’ needs. Calculate your debts, ongoing expenses, and future financial requirements like children’s education or retirement planning for your spouse. This assessment will help you understand if such a substantial policy is necessary and justifiable.

          Determine the Type of Policy

          Decide between term life insurance and permanent life insurance (such as Whole Life Insurance or Universal Life Insurance). Term Life Insurance is comparatively a more affordable option and offers coverage for a specific period, making it suitable if you need the policy for certain years, like until your mortgage is paid off or your children are financially independent. Permanent life insurance, on the other side, offers lifelong coverage and includes an investment component, making it more expensive but beneficial for long-term financial planning and estate preservation.

          Shop and Compare Quotes

          Get quotes from multiple insurance providers to compare premiums, coverage options, and policy terms. Each insurer has different underwriting criteria, which can affect the cost and availability of a policy. Use online tools or consult with insurance brokers who can provide quotes from various insurers and provide you support on the best options based on your needs.

          Evaluate Insurer’s Financial Stability

          It’s important to choose an insurer with strong financial stability, especially for a policy of this magnitude. Check the insurer’s ratings through agencies like A.M. Best or Moody’s to ensure they are financially capable of paying out a large claim.

          Prepare for the Underwriting Process

          The underwriting process for a Million-Dollar Life Insurance Policy is typically thorough. It will likely involve a medical exam, a review of your medical history, and possibly a lifestyle assessment. Be prepared to provide detailed information about your health, occupation, hobbies, and any risky activities you partake in.

          Complete the Application

          Fill out the insurance application with accurate and comprehensive information. Any misinformation or omission can lead to issues with policy approval or claim settlement.

          Review the Policy Before Finalizing

          Once your application is approved and you receive the policy documentation, please review it carefully. Ensure that all the details are correct and that you understand the policy’s terms and conditions, including the coverage, exclusions, premiums, and any riders or additional benefits.

          Consider Future Scalability

          With changing financial situations, you might want to increase your coverage in the future. Check if the policy allows for increasing the death benefit or adding riders later on.

          Finalize Your Purchase

          After a thorough review and understanding of the policy, complete the purchase. Keep all documentation in a safe place and inform your beneficiaries about the policy details.

          Regularly Review Your Policy

          Your financial situation and insurance needs can change over time. It is important to keep reviewing your policy regularly to make sure it still meets your needs and consider adjustments if necessary.

          Purchasing a Million-Dollar Life Insurance Policy in Canada is a significant financial decision that can provide immense peace of mind and security for your loved ones. It’s essential to approach this process with diligence and thoroughness to ensure the policy you choose aligns perfectly with your financial goals and family’s needs.

          Get The Best Insurance Quote From Canadian L.I.C

          Call 1 844-542-4678 to speak to our advisors.

          Canadianlic best insurance quote

          When does a dollar life insurance policy make sense?

          In Canada, a Million-Dollar Life Insurance Policy may seem like a substantial coverage amount, but there are several scenarios where such a policy makes perfect sense. Here are some situations that warrant considering a policy of this magnitude:

          High-Income Earners

          For individuals with a high income, a million-dollar policy can be necessary to ensure that their family maintains their standard of living in the event of their untimely death. This is especially relevant for those who are the primary or sole breadwinners in their family. The policy can provide several years’ worth of income replacement, helping the family to adjust financially.

          Large Financial Obligations

          Suppose you have significant financial commitments, such as a hefty mortgage, business loans, or other substantial debts. In that case, a million-dollar policy can ensure that these obligations are not passed onto your family after your death. It provides a financial cushion to settle outstanding debts without burdening your loved ones.

          Future Goals and Aspirations for Dependents

          If you have specific future financial goals for your dependents, like funding your children’s higher education, ensuring a comfortable retirement for your spouse, or other long-term plans, a million-dollar policy can help realize these aspirations without your financial contribution in the future.

          Estate Planning and Legacy Creation

          For those involved in estate planning, particularly individuals with sizable estates, million-dollar life insurance policies can be a strategic tool. It can help in covering estate taxes, thus preserving the estate’s value for the beneficiaries, and can also be used to leave a substantial financial legacy to heirs or charities.

          Business Owners

          Business owners or partners in a business might consider a million-dollar policy as part of a buy-sell agreement or as key person insurance. This makes it possible for the business to continue operating or transition smoothly without financial hardship in the event of their death.

          Protecting Against Inflation

          Considering the impact of inflation over time, especially for those planning long-term, a million-dollar policy ensures that the death benefit remains substantial even as the cost of living increases.

          Diverse Financial Safety Net

          For those looking to provide a comprehensive financial safety net that covers various aspects – from daily living expenses to future significant expenditures – a policy of this size can be an all-encompassing solution.

          Conclusion

          In conclusion, a Million-Dollar Life Insurance Policy in Canada is a viable option for many, especially those with significant financial responsibilities or ambitions for their family’s future. It’s a commitment that should be made after careful consideration of your financial situation, future goals, and the needs of your dependents. Consulting with an insurance specialist can provide valuable insights and guidance in deciding if such a policy is suitable for you. When thoughtfully chosen, a Million-Dollar Life Insurance Policy can be an integral part of your financial strategy, offering peace of mind and security for your loved ones.

          Faq's

          A million-dollar life insurance policies are typically suited for individuals with significant financial obligations, such as a large mortgage or sizable debts, or those with high income looking to replace their earnings for their dependents. It’s also beneficial for those focused on estate planning or wanting to leave a considerable financial legacy.

          The cost varies based on several factors, including the type of policy (term or permanent), the policyholder’s age, health, lifestyle choices (like smoking), and the underwriting policies of the insurance company. Generally, younger and healthier individuals pay lower premiums.

          Qualification depends on the severity and nature of the health issues. While certain health conditions may increase premiums or limit options, many insurers offer policies for individuals with various health concerns. It’s important to provide accurate health information during the application process.

          In most cases, yes. For a policy of this size, insurers typically require a comprehensive medical examination to assess the risk accurately. However, some insurers might offer policies with limited coverage or higher premiums without a medical exam.

          Yes, many policies allow you to increase your coverage, subject to underwriting approval at the time of the request. It’s important to review your policy terms or consult with your insurance provider for specific options available in your policy.

          Look for providers with strong financial stability, good customer service, and competitive pricing. Checking independent ratings, reading customer reviews, and comparing quotes from different insurers can help in making an informed decision.

          Choosing between term and permanent life insurance depends on your financial goals, the duration of coverage needed, and your budget. Term life is more affordable and suitable for temporary coverage needs, while permanent life offers lifelong coverage and includes a cash value component.

          While it’s possible to purchase life insurance without an agent, consulting with a licensed insurance professional like Canadian LIC can be beneficial. They can give you valuable advice, and help you navigate the options, and assist in the application process.

          In Canada, the death benefit from a life insurance policy is generally received tax-free by the beneficiaries. However, it’s recommended to consult with a financial advisor for specific tax advice related to your policy and estate planning.

          The time of approval can vary depending on the underwriting process, the completeness of your application, and whether additional medical information is required. Typically, it can take a few weeks to several months for a policy of this size to be fully underwritten and approved.

          The above information is only meant to be informative. It comes from Canadian LIC’s own opinions, which can change at any time. This material is not meant to be financial or legal advice, and it should not be interpreted as such. If someone decides to act on the information on this page, Canadian LIC is not responsible for what happens. Every attempt is made to provide accurate and up-to-date information on Canadian LIC. Some of the terms, conditions, limitations, exclusions, termination, and other parts of the policies mentioned above may not be included, which may be important to the policy choice. For full details, please refer to the actual policy documents. If there is any disagreement, the language in the actual policy documents will be used. All rights reserved.

          Please let us know if there is anything that should be updated, removed, or corrected from this article. Send an email to Contact@canadianlic.com or Info@canadianlic.com

          Life Insurance Policy Form