- Connect with our licensed Canadian insurance advisors
- Schedule a Call

Basics
Common Inquiries
BASICS
- Is Infinite Banking A Smart Financial Strategy?
- Understanding the Infinite Banking Concept
- Why Infinite Banking Appeals to Canadians Seeking Financial Freedom
- How Infinite Banking Strategy Helps Build Financial Independence
- Challenges and Misconceptions About Infinite Banking
- Who Should Consider Infinite Banking for Financial Freedom?
- How to Start Your Infinite Banking Journey
- Key Advantages of the Infinite Banking Strategy
- A Day-to-Day Struggle: Why More Canadians Are Exploring Infinite Banking
- Potential Drawbacks You Should Know
- The Future of Infinite Banking in Canada
- Is Infinite Banking a Smart Financial Strategy?
COMMON INQUIRIES
- Can I Have Both Short-Term and Long-Term Disability Insurance?
- Should Both Husband and Wife Get Term Life Insurance?
- Can I Change Beneficiaries on My Canadian Term Life Policy?
- What Does Term Life Insurance Cover and Not Cover?
- Does Term Insurance Cover Death?
- What are the advantages of Short-Term Life Insurance?
- Which Is Better, Whole Life Or Term Life Insurance?
- Do Term Life Insurance Rates Go Up?
- Is Term Insurance Better Than a Money Back Policy?
- What’s the Longest Term Life Insurance You Can Get?
- Which is better, Short-Term or Long-Term Insurance? Making the Right Choice
IN THIS ARTICLE
- What is the minimum income for Term Insurance?
- How Does Income Affect Your Term Life Insurance Policy?
- Can You Buy Term Life Insurance Online with a Low Income?
- How Can You Lower Your Term Life Insurance Cost?
- How Much Term Life Insurance Do You Need?
- Can Your Term Life Insurance Policy Be Adjusted Over Time?
- Why Term Life Insurance Is Ideal for Lower-Income Canadians
- Final Thoughts
- More on Term Life Insurance
Can I Add Riders To A Money-Back Life Insurance Policy?
By Pushpinder Puri
CEO & Founder
- 13 min read
- Oct 13, 2026
SUMMARY
Money Back Life Insurance Policy Canada options can become far more flexible with the right riders. Coverage includes topics such as Cash Back Life Insurance, death benefit structures, guaranteed insurability rider options, child term rider benefits, accelerated death benefit rider features, cash value growth, Money Back Vs Endowment Plan comparisons, and long-term financial protection strategies designed around evolving financial goals and family needs.
Introduction
The way Canadians look at Life Insurance has changed dramatically in recent times. Canadians no longer consider their insurance policies as a payment that they receive only upon death. Today, Canadians require a certain amount of flexibility. They require policies that will adapt according to changing times. They require policies that would not only help with their retirement needs, educate their children, plan their estates, and cover emergencies but also financially secure their dependents.
This explains why more and more Canadians are interested in Money Back Life Insurance policies.
According to the Canadian Life and Health Insurance Association, more than 29 million Canadians currently own Life Insurance coverage, and permanent insurance products continue gaining popularity because families increasingly want financial products that combine protection with savings-related benefits. Industry data published by CLHIA also shows Canadians are paying greater attention to long-term financial resilience and estate protection.
At Canadian LIC, one question repeatedly comes up during consultations involving Cash Back Life Insurance:
“Can I add riders to improve the policy later?”
The answer is yes in most cases. The policy owner can modify a regular policy to become much more personalized. Nevertheless, it will really pay off only when the owners are able to choose the correct riders based on their financial needs.
There are riders designed to increase the flexibility of the policies in case of certain medical problems. There are those who aim to ensure that your kids get protected, that you stay insurable in the future, or that you gain additional protection in case of unforeseen circumstances. Nevertheless, many people buy unnecessary riders, while others ignore the riders which might be critical to them.
Learning about what is called riders can help you make better choices.
What Is Money Back Life Insurance And How Does It Work?
Understanding riders requires that one first understand the meaning of Money Back Life Insurance and why this type of Life Insurance is viewed differently by many people in Canada when compared to ordinary term Life Insurance.
Money Back Life Insurance refers to a situation whereby, together with providing Life Insurance cover, the policy gives periodic payouts to the insured in the event that they are alive at the point of payout. This is unlike other ordinary term insurance policies, whereby premium payments are purely to compensate the insured for any risks during the specified term.
The Money Back Plan provides the insured with a mix of protection and savings benefits.
In most Long Term Money Back Insurance Plans, the insured person is entitled to receive periodic payout throughout the period they remain insured, even though they continue enjoying death cover. Should the insured pass away before the expiration of the contract term, the entire total death cover is paid out to the listed beneficiary.
Canadians like Life Insurance with money-back guarantees due to psychological reasons of not “losing” premiums in case of no payout.
That emotional factor matters more than many people realize.
Our customers have described term insurance as being a necessity, although an unpleasant one, since the individual does not stand to receive anything if they outlive their coverage period. The idea behind Money Back Life Insurance, however, shifts the client’s understanding, as the payment made might eventually yield returns on the policy.
There are cases where some Life Insurance policies are built to earn interest over time, giving the customer the option of utilizing policy loan possibilities when necessary.
However, just like the concept of term and permanent, not all Money Back Plans are the same.
Some permanent Life Insurance policies will lower the benefit amount upon making survival payments to the insured, while some will retain the total benefit amount. Some of these will focus primarily on the insured living throughout the policy period, while others operate more like investment vehicles with insurance coverage included.
It is here that expertise comes in handy, as some of the language used differs from one insurer to another, depending on the type of product they sell.
Customers also tend to get confused by Money Back Vs Endowment Plans because they both carry savings components.
Why Canadians Add Riders To A Life Insurance Policy
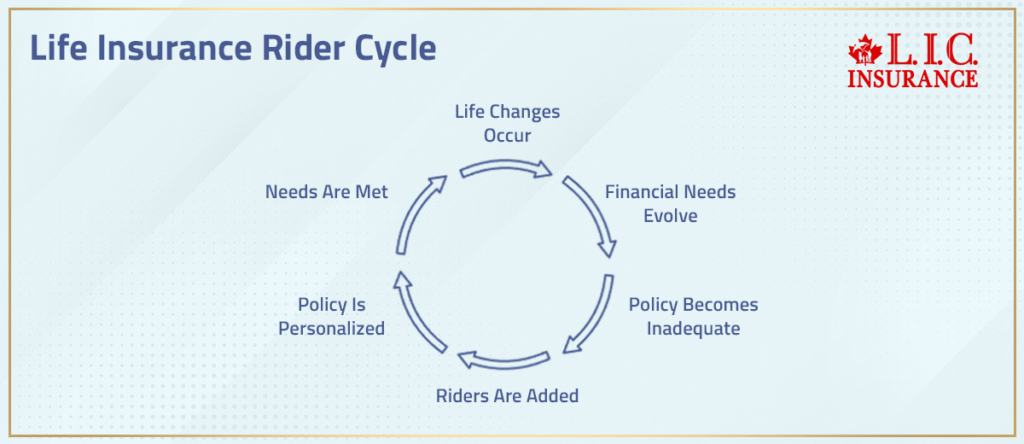
Life changes faster than most people expect.
The person buying Life Insurance at 30 can encounter children, work issues, parents growing old, mortgage payments, planning for retirement, or health problems.
What was initially bought as an essential insurance policy twenty years before might not be adequate anymore due to different financial needs.
This is where the importance of the riders comes in.
Life Insurance rider is an extra benefit that could be added to your main policy that will give you more insurance coverage or special features.
Riders give the opportunity for a person to personalize his or her insurance package without being stuck to the standardization of Life Insurance offered in Canada.
Clients of Canadian LIC often find themselves seeking for rider services after significant life events happen to them.
Some parents become preoccupied with education costs of their kids, some worry because they see people close to them getting sick. Business owners tend to worry about estate or income taxes. Young working people worry that they may lose insurability in the future.
These concerns explain why insurance rider flexibility has become increasingly important within modern financial planning.
Still, adding riders should never happen randomly.
A common misconception among Canadians is that all riders help improve the policy. However, it should be noted that all riders contribute to the increased cost of the total policy. Some riders incur a relatively smaller additional cost, but other riders cause substantial increments in insurance premiums.
An ideal scenario would involve balancing affordability, protection, and long-term financial protection needs.
For instance, a young and healthy client might benefit much more from guaranteed insurability than any other rider since the medical examinations will become more challenging in the future. Conversely, a client who is close to retiring might prefer a flexible accelerated death benefit or efficient estate planning strategy.
It all depends on personal circumstances.
Understanding The Death Benefit In Money Back Life Insurance Policies
Even though Money Back Life Insurance Policy Canada includes survival benefits, the death benefit remains the core purpose of the policy.
This is one area where confusion often occurs.
Many think that since the payout happens during the term, the remainder becomes less effective. That is not always the case. The structure very much depends on the way in which the insurance company creates the permanent policy.
Some insurance companies will keep the benefit even in spite of survival payments, while others will decrease the death benefit with each payment.
It should be advised at Canadian LIC for clients to look very carefully into how their particular insurance company deals with the issue, as it may vary greatly from insurer to insurer.
One illustration would be policies with same premiums but resulting in quite different benefits after twenty years of payments.
In general, when the covered individual passes away under an ongoing policy, his/her heirs usually receive the remainder of the death benefit tax-free in Canada.
Beneficiary changes also become important throughout life.
Factors such as marriages, divorces, transfers of business interests, remarriages, and further additions to families may all play a role in how distribution of benefits should take place. The problem is that many people overlook this aspect and do not update beneficiaries, leading to legal challenges later on.
Emotionally, the fact is clear; in times of crisis, a family needs financial coverage right away. Loan payments, mortgage, debts, tuition fees, and burial costs are all ongoing regardless of whether someone has a steady income anymore.
This is why the overall structure of the death benefits is far more important than comparing premiums only.
Which Insurance Rider Options Are Available With Cash Back Life Insurance?
All insurance companies that sell money-back insurance also provide options for adding riders to the existing policy. It is not available everywhere; its availability will depend upon age, health condition, underwriting guidelines, and the insurance company.
There are riders that you can opt for when applying for an insurance plan and some that can be added afterwards under certain conditions.
Some common types of riders are accelerated death benefit rider, guaranteed insurability rider, child term rider, accidental death benefit, and waiver of premium rider, among others.
Our clients are sometimes astonished at how different insurers approach rider availability.
An insurer could allow a guaranteed insurability right up to 45 years old, while another would deny it to someone far younger. While some plans will make an additional rider contingent on a medical test, others might be more lenient and approve them easily.
Earlier rider addition translates into a lower cost, usually.
This means that people who try to add riders later because of health conditions could end up paying significantly more.
One more critical detail to know when talking about riders is that they can vary greatly by utility.
Some riders are very useful when you have kids, but useless to retirees. Other riders will appeal only to those in a certain profession and are unnecessary to anyone else.
Therefore, customizations should never be based on assumptions.
Accelerated Death Benefit Rider: Early Access During A Terminal Illness
One of the most emotionally significant riders offered is the accelerated death benefit rider.
Under the provisions of this rider, the policyholder may receive a portion of the death benefit if he or she is terminally ill. The financial situation of those who are terminally ill is extremely challenging at times when they have already been emotionally drained.
Financial strains due to travel expenses, medical expenses, and loss of income make the situation even worse for the families of the terminally ill.
Our clients enjoy this rider since it allows flexibility during those times when additional financial pressure does not need to be added to their families.
Based on the insurance company, the rider could offer access to some percentage of the death benefit when the insured gets diagnosed with a terminal illness and is expected to pass away shortly thereafter.
Additionally, the policies might have conditions involving severe or total disabilities as well.
Clearly, the usage of the accelerated death benefit will result in a lower death benefit that can be received by beneficiaries.
However, this trade-off is deemed appropriate by many families due to the fact that the money arrives at precisely the time it is needed.
The rider will benefit Canadians worrying about health care interruptions.
Guaranteed Insurability Rider: Future Coverage Without Another Medical Exam
Health can change unexpectedly.
One who enjoys good health at the age of 30 can develop diabetes, heart disease, autoimmune diseases, and cancer by the time he or she reaches the age of 45 years old. After health problems develop, getting new insurance becomes complicated or expensive.
It is the reason why guaranteed insurability becomes one of the most valuable riders in insurance.
With the guarantee of insurability, an insured is able to acquire additional coverage in the future without undergoing a medical examination again.
It becomes highly essential when someone undergoes life changes such as marriage, childbirth, an increase in income, expansion in business, and a mortgage increase.
At Canadian LIC, the insurance rider is usually advised for younger families as it covers future flexibility when health problems become an issue. Many Canadians do not realize how much their premiums rise after they develop some health problems. Buying insurance now can potentially save hundreds of thousands of dollars throughout a lifetime.
Child Term Rider And Money Back Policy For Child Education
Parents naturally worry about protecting their children financially, but many also want to secure future insurability for them early.
A child term rider provides limited Term Life Insurance coverage for children under the parent’s insurance policy.
While the death benefit itself may not be large, the real long-term value often involves future conversion opportunities. Many child term rider structures allow children to convert coverage into permanent Life Insurance later without another medical exam.
That feature can become extremely valuable if future health complications arise.
At Canadian LIC, parents exploring a Money Back Policy for child education often combine education-focused savings strategies with child protection riders to create broader family-oriented financial planning.
The emotional appeal is understandable.
Parents do not simply want short-term coverage. They want stability for the child’s future regardless of what happens medically later in life.
Some parents also view child-related riders as a disciplined financial planning tool because it encourages long-term thinking instead of reactive financial decisions.
Accidental Death Coverage: Is The Additional Cost Worth It?
An accidental death rider enhances payouts in case of death caused by qualifying accidents.
Sometimes the payout will be twice the amount of the original death benefit payment.
This kind of additional coverage is very popular with those engaged in physically intensive occupations.
Nevertheless, accidental death riders are sometimes very misinterpreted.
There are many assumptions that nearly any accidental death case fits, but exceptions are quite many and vary with insurance firms.
Any accident connected with risky actions, drug consumption, criminal acts or occupations can be non-qualifying accidents.
At Canadian LIC, it is advisable to review your policy regarding accidental death riders, as not all of them guarantee a good return on money.
Some people could get better protection in terms of enhancing the original death benefit than getting accidental coverage.
Nevertheless, in case of some occupations and their risks, accidental death riders might still be worth considering.
Money Back Vs Endowment Plan: Which One Offers Better Flexibility?
| Feature | Money Back Policy | Endowment Plan |
|---|---|---|
| Survival Benefits | Periodic payouts | Lump sum at maturity |
| Liquidity | Higher | Lower |
| Rider Flexibility | Usually broader | Often limited |
| Cash Flow Frequency | Multiple intervals | End of term |
| Death Benefit | Active during term | Active during term |
| Investment Orientation | Moderate | Stronger savings focus |
| Flexibility | Higher | More restrictive |
The individuals wondering whether Money Back Plans constitute a safe investment option must be aware that the insurance products were created to provide stable solutions and protection for their owners. While compared to market-linked products, the Money Back Insurance provides better prediction of results and less volatility, it might lack some growth options which equity investments possess.
All discussions at the Canadian LIC regarding whole life and term insurance products as well as endowments, will first address financial considerations rather than unrealistic expectations from these investments.
Is Money Back Insurance Taxable In Canada?
Questions involving taxation are extremely common.
One of the most frequently asked questions by many individuals in Canada is whether there is any tax on survival payments, withdrawal of policy loans, or growth.
Typically, conventional death benefit amounts that have been paid out to beneficiaries will not result in taxes being levied in Canada. Nonetheless, it is quite possible to get into taxation issues in permanent Life Insurance where one is seeking to handle accumulated growth, surrender values, and policy loans.
Money Back Insurance taxation questions must always involve consulting both the insurance agent and the tax expert.
For instance, withdrawals may end up becoming taxable based on adjusted cost basis. In addition, interest accumulation in certain insurance policy forms may be subject to taxes at some point.
Canadian LIC advises clients who are using permanent Life Insurance as an estate and wealth planning tool to consult tax experts.
Can Seniors Add Riders To Money Back Life Insurance Policies?
Yes, although options become more limited with age.
Age is a factor that affects the availability of riders beyond certain ages, particularly where there are health-related problems.
Nevertheless, the relevance of Money Back Insurance for senior citizens continues because of estate protection, burial expenses, last-minute tax payment, and support for surviving dependents, among other considerations for many Canadian households.
There are some cases where a simplified insurance can be issued without a complete physical examination, but premiums will be higher than those for early policies.
At Canadian LIC, many older customers tend to focus on riders related to death benefits, long-term care or coverage stability rather than fast savings.
It is quite clear that insurance becomes costly as one grows older.
However, just because an individual is a senior citizen, this does not imply that he or she does not need insurance at all.
How Much Coverage Should You Choose?
One of the most difficult parts of Life Insurance planning involves determining how much coverage truly makes sense.
There is no universal formula because every family’s financial situation differs.
At Canadian LIC, coverage discussions typically involve reviewing:
- Mortgage obligations
- Income replacement needs
- Child education costs
- Retirement objectives
- Business liabilities
- Existing investments
- Future inflation concerns
Most Canadians unknowingly end up underinsuring themselves in their quest for affordability at present.
A plan purchased 20 years ago may not necessarily suit the current needs of a household.
This is one more reason why riders are important.
One should not just aim at securing insurance at affordable rates.
One should aim at securing sustainable insurance plans to help one in the times ahead.
Common Mistakes Canadians Make When They Add Riders
One of the major mistakes made by Canadians is purchasing various riders without really assessing whether these features fit their financial objectives.
A second common problem relates to buying plans based on the cost of initial premiums and disregarding that additional riders might lead to higher costs down the road.
Another group of people neglects to reassess the adequacy of their insurance. Since situations can change for the worse, the existing plan may no longer fit the client’s needs.
Other mistakes are related to misinterpretations of exclusions, letting policies lapse, forgetting about beneficiary changes, or believing that all riders are beneficial for the plan.
At Canadian LIC, policy review is highly recommended since an effective insurance plan is supposed to evolve along with the client’s life situation.
How Canadian LIC Helps Families Customize Money Back Life Insurance Policies
No two families approach insurance the same way.
Some prioritize retirement stability. Others focus on child education planning, estate transfer efficiency, or long-term financial protection against health-related uncertainty.
At Canadian LIC, the process starts with understanding the client’s financial goals before recommending any policy structure.
That includes reviewing:
- Existing assets
- Long-term obligations
- Tax considerations
- Coverage affordability
- Rider suitability
- Future insurability concerns
- Estate planning objectives
Given that there are various ways in which insurers construct Money Back Life Insurance quotes, there is a critical need for comparative analysis.
The emphasis here is not on the sales of insurance.
The emphasis here is on the construction of protection measures that can stand the test of time.
For many Canadians, the proper choice of riders becomes just as crucial as the choice of the actual policy.
Author: Harpreet Puri, Licensed Insurance Adviser | MDRT Qualifier
Experience: 14 Years In Life Insurance & Financial Planning
LinkedIn Profile:https://www.linkedin.com/in/harpreetpuricanadianlic/
Disclaimer:
This content is provided for general educational purposes only and should not be considered legal, tax, or financial advice. Life Insurance policy features, rider availability, premiums, and eligibility rules vary depending on the insurance provider and individual circumstances. Tax treatment involving permanent Life Insurance, cash value, or policy loans may differ based on personal financial situations. Readers should consult a licensed insurance professional and a qualified tax advisor before making coverage or financial planning decisions.
FAQs
There could be some lenders who would accept the permanent policy if its cash value can be considered enough for their lending purposes. The eligibility for a loan from such policies is dependent on the insurance company, cash value of the policy, and the lender’s criteria.
Certainly, occupation does play an important role in the determination of the premium for the policy. Those individuals engaged in dangerous occupations may end up paying higher premiums. Insurance companies’ criteria include consideration of factors such as travel and occupational exposures.
A number of insurers offer permanent Life Insurance applications to new arrivals; however, it is possible that a residency status and Canadian financial record might impact the conditions of acceptance. Additionally, it is quite possible that some policies will ask for more paperwork during the underwriting process.
Most of the time, smoking will result in higher insurance costs since smoking is categorized as a higher risk by insurance companies. Even people who smoke occasionally may have to pay more in premiums. People who abstain from smoking for a number of years can benefit from better premiums.
In some cases, the rules for policies related to dependants or spouses may be such that different combinations of insurance riders could be used based on the individual requirements of each person. The kind of flexibility will differ based on the insurance company and the policy type.
Certainly, today, many insurance companies provide online applications for Life Insurance with a money-back guarantee. Nonetheless, due to the complexity of the policy structures in some cases, the assistance of an advisor is necessary when developing a customer’s financial plan.
Some people in Canada would rather have Cash Back Life Insurance as opposed to market-linked financial products since there is relative stability when it comes to economic uncertainty. Although profits might be relatively low, there are certain advantages for families that need security.
Life Insurance needs can be reassessed when a family decides to increase its obligations in the home. In accordance with the structure of the insurance policy, the insured person will have a variety of riders and policy upgrade possibilities for acquiring more coverage.
Not necessarily. Some simplified issues or limited underwriting products will provide coverage without the need for a thorough medical examination process. Nonetheless, some policies without medical examination tend to be more expensive or have fewer coverage limits than underwritten permanent Life Insurance.
Some permanent policy structures with accumulation of cash value can later be incorporated into a wider retirement plan. Some policy owners make use of cash value accumulation, access to policy loans, and survival benefits in supplementing their flexibility options at retirement.
Indeed, there are those business owners who utilize permanent Life Insurance as a means of ensuring that their businesses have adequate protection in case of a key person risk. However, in some instances, the policy benefits can be used for operational stability following the death of a key person.
Some insurance products offered by companies offer shorter periods of premium payment along with longer periods of coverage. This is beneficial for people who want to remain covered throughout their lives but do not want to pay any premiums after retirement.
Insurers allow you to maintain your coverage even when residing outside for some time, although conditions for this may vary by insurer. Long stays may influence eligibility criteria for additional insurance riders. It is advisable to consult the insurance provider about travel plans.
The dividends for some of the permanent policies that participate in this program may arise depending on the performance of the insurer. The policy owners can then use the dividend to either reduce the premiums paid, buy more coverage or build up even more cash value.
The payment frequency for many insurers is flexible after the start of the insurance policy. There may be instances when people opt for annual payments due to small discounts offered by insurers in comparison to monthly payment plans.
Some riders may be allowed to automatically expire beyond a particular age or coverage stage even though the permanent insurance policy continues. Some other riders will be available for the entire duration of the policy. It is important to note how riders expire to prevent any surprises later on.
Some families purchase permanent Life Insurance for their dependents who will need long-term financial support. If structured correctly, this can assist in providing funding for the care of one of the family members. This type of planning generally requires estate or trust planning assistance.
Yes, certainly, because high inflation will decrease the buying capacity of the Life Insurance payment received after many years. People who select Money Back Life Insurance plans take into account how future expenses for the family might grow significantly.
Some of the joint insurance plans have individual rider options for each individual insured. While one spouse may want extra cover on the medical front, another may be concerned more about guaranteed insurability and future policy options. This depends on which insurance company it is.
The following are some of the rider benefits that might include the waiting period before becoming claimable. These are often applied to the specialized health or disability riders. It is crucial to understand this since the interpretation of the cover differs from what the contract means.
Ownership transfers can be done depending on the type of permanent Life Insurance coverage chosen. There are individuals who make ownership transfers due to various reasons like tax issues and other financial planning issues related to their businesses or families.
The use of more riders at times might lead to the reduction in accumulation rate of cash values since part of the premiums pay for benefits from the additional riders. This will depend on the type of permanent insurance policy that is adopted.
Other Canadians use their Life Insurance for donation planning in later life. Making a registered charity the recipient of a policy can provide an avenue to further one’s charitable intent, as well as generate estate taxation benefits in some cases.
Overall, the more youthful and healthy an individual is, the more favourable prices they get from the insurer, due to low risks involved. Taking out a life cover early can increase the chances of getting a wide variety of riders at lower costs in future due to health problems.
The answer is yes because there are many instances where families fail to appreciate the monetary benefits of unremunerated responsibilities within their family homes. Riders and additional policies can assist in compensating for such things when a stay-at-home parent falls ill or dies.
Sources and Further Reading
- Canadian Life And Health Insurance Association (CLHIA) – Canadian Life And Health Insurance Facts 2025
Comprehensive Canadian industry statistics on Life Insurance coverage, permanent Life Insurance trends, claims payouts, and household protection levels. - CLHIA Official Website
Industry guidance, consumer education resources, and updates related to Canadian Life Insurance products and regulations. - Sun Life Financial Canada
Information on permanent Life Insurance, whole Life Insurance, cash value growth, and optional insurance rider features available in Canada. - Manulife Canada Life Insurance
Educational resources discussing Life Insurance coverage, guaranteed insurability, policy flexibility, and long-term financial protection. - Canada Life Insurance Solutions
Resources related to permanent Life Insurance policies, term Life Insurance, rider options, and estate-focused planning strategies. - Canada Revenue Agency (CRA) – Life Insurance Policy Information
Official Canadian tax guidance involving Life Insurance policy taxation, policy loans, beneficiary treatment, and tax-free death benefit considerations. - Financial Services Regulatory Authority Of Ontario (FSRA)
Regulatory guidance related to licensed insurance professionals, consumer protection, and insurance compliance standards in Canada. - Assuris – Protection For Canadian Policyholders
Information explaining consumer protection coverage for Canadian Life Insurance policyholders if a member insurance company fails financially. - Investment Executive – Insurers Paid Record Benefits In 2023: CLHIA
Industry reporting on rising Life Insurance protection levels, growing permanent policy demand, and Canadian household coverage trends. - Insurance Business Canada – Record Insurance Benefit Payouts In Canada
Coverage discussing the Canadian insurance industry growth, disability benefits, retirement solutions, and increasing demand for long-term financial protection.
Key Takeaways
- A Money Back Life Insurance Policy Canada combines Life Insurance coverage with scheduled survival payouts, making it appealing for Canadians seeking both protection and long-term financial value.
- Riders can significantly improve a Life Insurance policy by adding additional protection tailored to evolving financial goals, family responsibilities, and future healthcare concerns.
- Popular rider options include accelerated death benefit rider features, guaranteed insurability rider benefits, child term rider protection, and accidental death coverage.
- Life Insurance with money back guarantee structures may help families feel more comfortable about paying premiums because some policies provide money returned during the policy term.
- The death benefit structure can vary depending on the insurance company, especially after survival payouts are issued, making policy comparison extremely important.
- Guaranteed insurability can help policyholders increase coverage later without another medical exam, which may become valuable if health issues develop in the future.
- Certain permanent Life Insurance policies may build cash value over time, allowing policyholders potential access to policy loan options or additional financial flexibility.
- Money Back Vs Endowment Plan comparisons should focus on liquidity, flexibility, rider availability, and long-term financial protection rather than investment returns alone.
- Questions involving is Money Back Insurance taxable should always be reviewed with a tax advisor because policy taxation may vary depending on policy structure and withdrawals.
- Adding too many riders without evaluating affordability can increase higher premiums and create long-term financial strain if the policy becomes difficult to maintain.
- Money Back Life Insurance for seniors may still offer valuable estate planning and financial protection opportunities, although rider availability often becomes more limited with age.
- Working with an experienced insurance professional helps families compare Money Back Life Insurance quotes properly and customize coverage according to real long-term financial goals instead of short-term assumptions.
Your Feedback Is Very Important To Us
IN THIS ARTICLE
- Can I Add Riders To A Money-Back Life Insurance Policy?
- What Is Money Back Life Insurance And How Does It Work?
- Why Canadians Add Riders To A Life Insurance Policy
- Understanding The Death Benefit In Money Back Life Insurance Policies
- Which Insurance Rider Options Are Available With Cash Back Life Insurance?
- Accelerated Death Benefit Rider: Early Access During A Terminal Illness
- Guaranteed Insurability Rider: Future Coverage Without Another Medical Exam
- Child Term Rider And Money Back Policy For Child Education
- Accidental Death Coverage: Is The Additional Cost Worth It?
- Money Back Vs Endowment Plan: Which One Offers Better Flexibility?
- Is Money Back Insurance Taxable In Canada?
- Can Seniors Add Riders To Money Back Life Insurance Policies?
- How Much Coverage Should You Choose?
- Common Mistakes Canadians Make When They Add Riders
- How Canadian LIC Helps Families Customize Money Back Life Insurance Policies
Sign-in to CanadianLIC
Verify OTP